Depreciation is the fixed asset subledger: it keeps one or more accounting books over your assets, calculates and posts each period’s charge, and hands the journals to your general ledger.
If you don’t see this in your navigation, your administrator can switch the module on under Administration → Modules, or it may not be included in your plan.
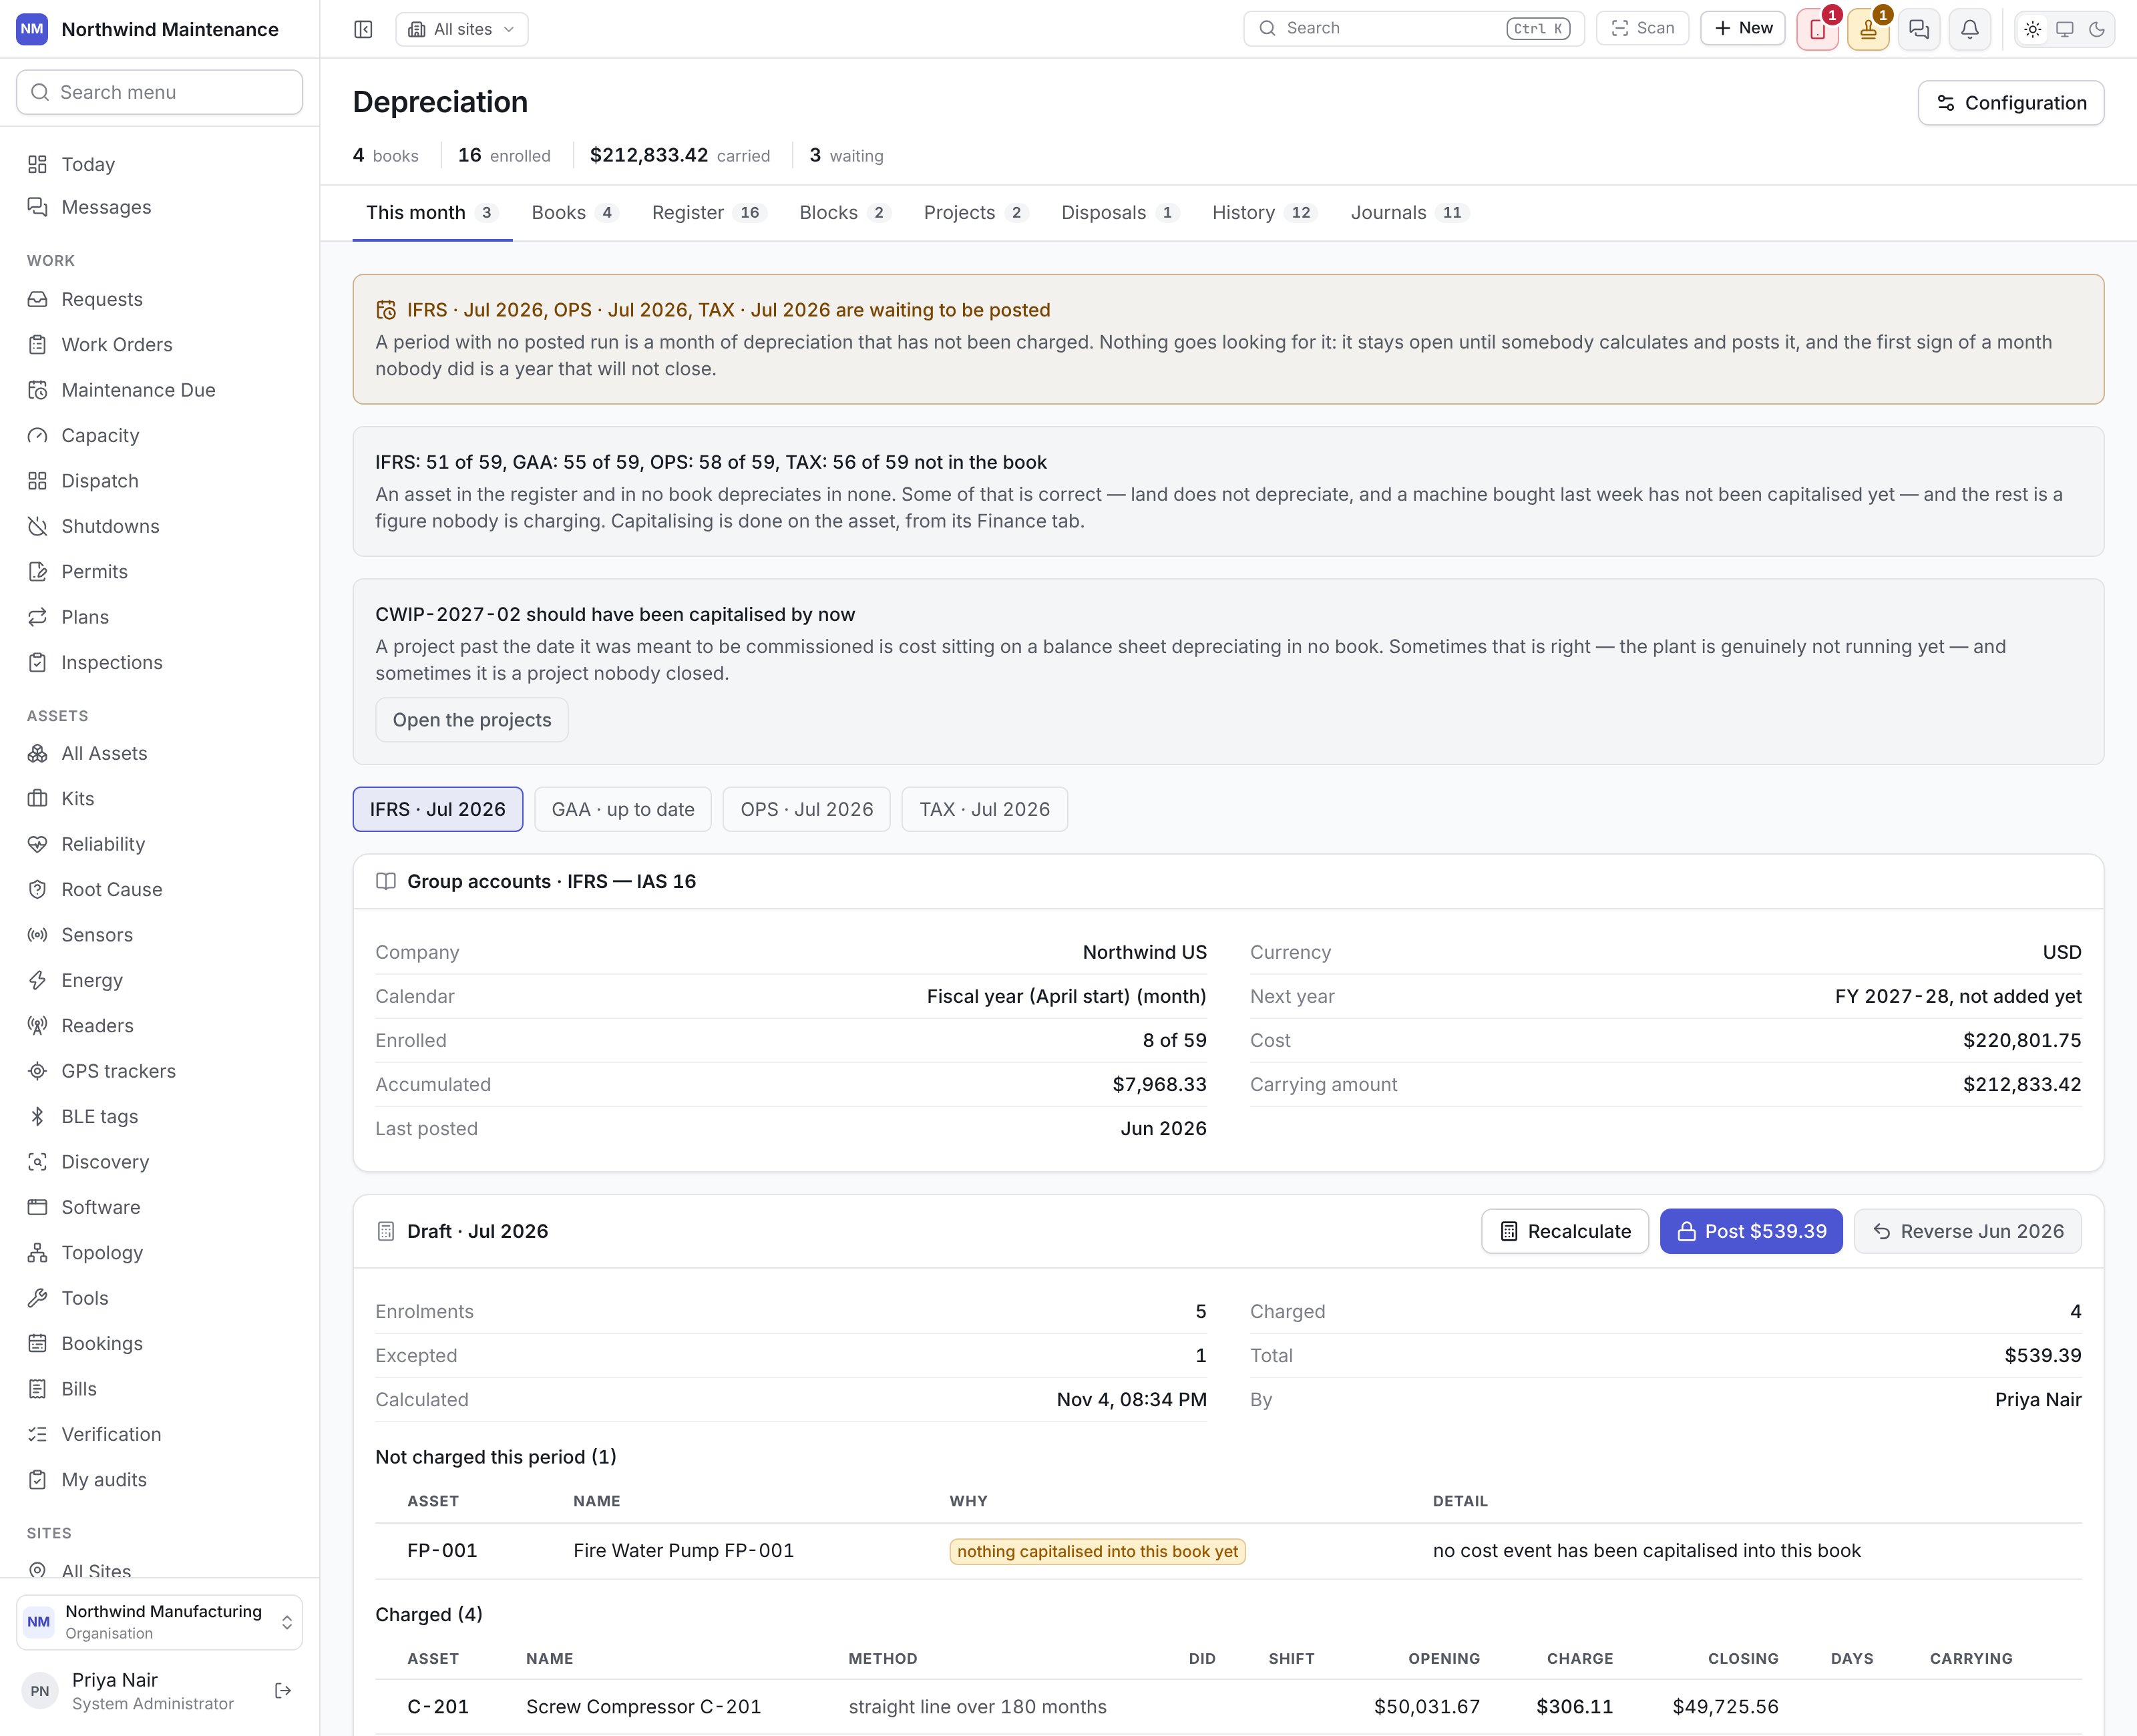
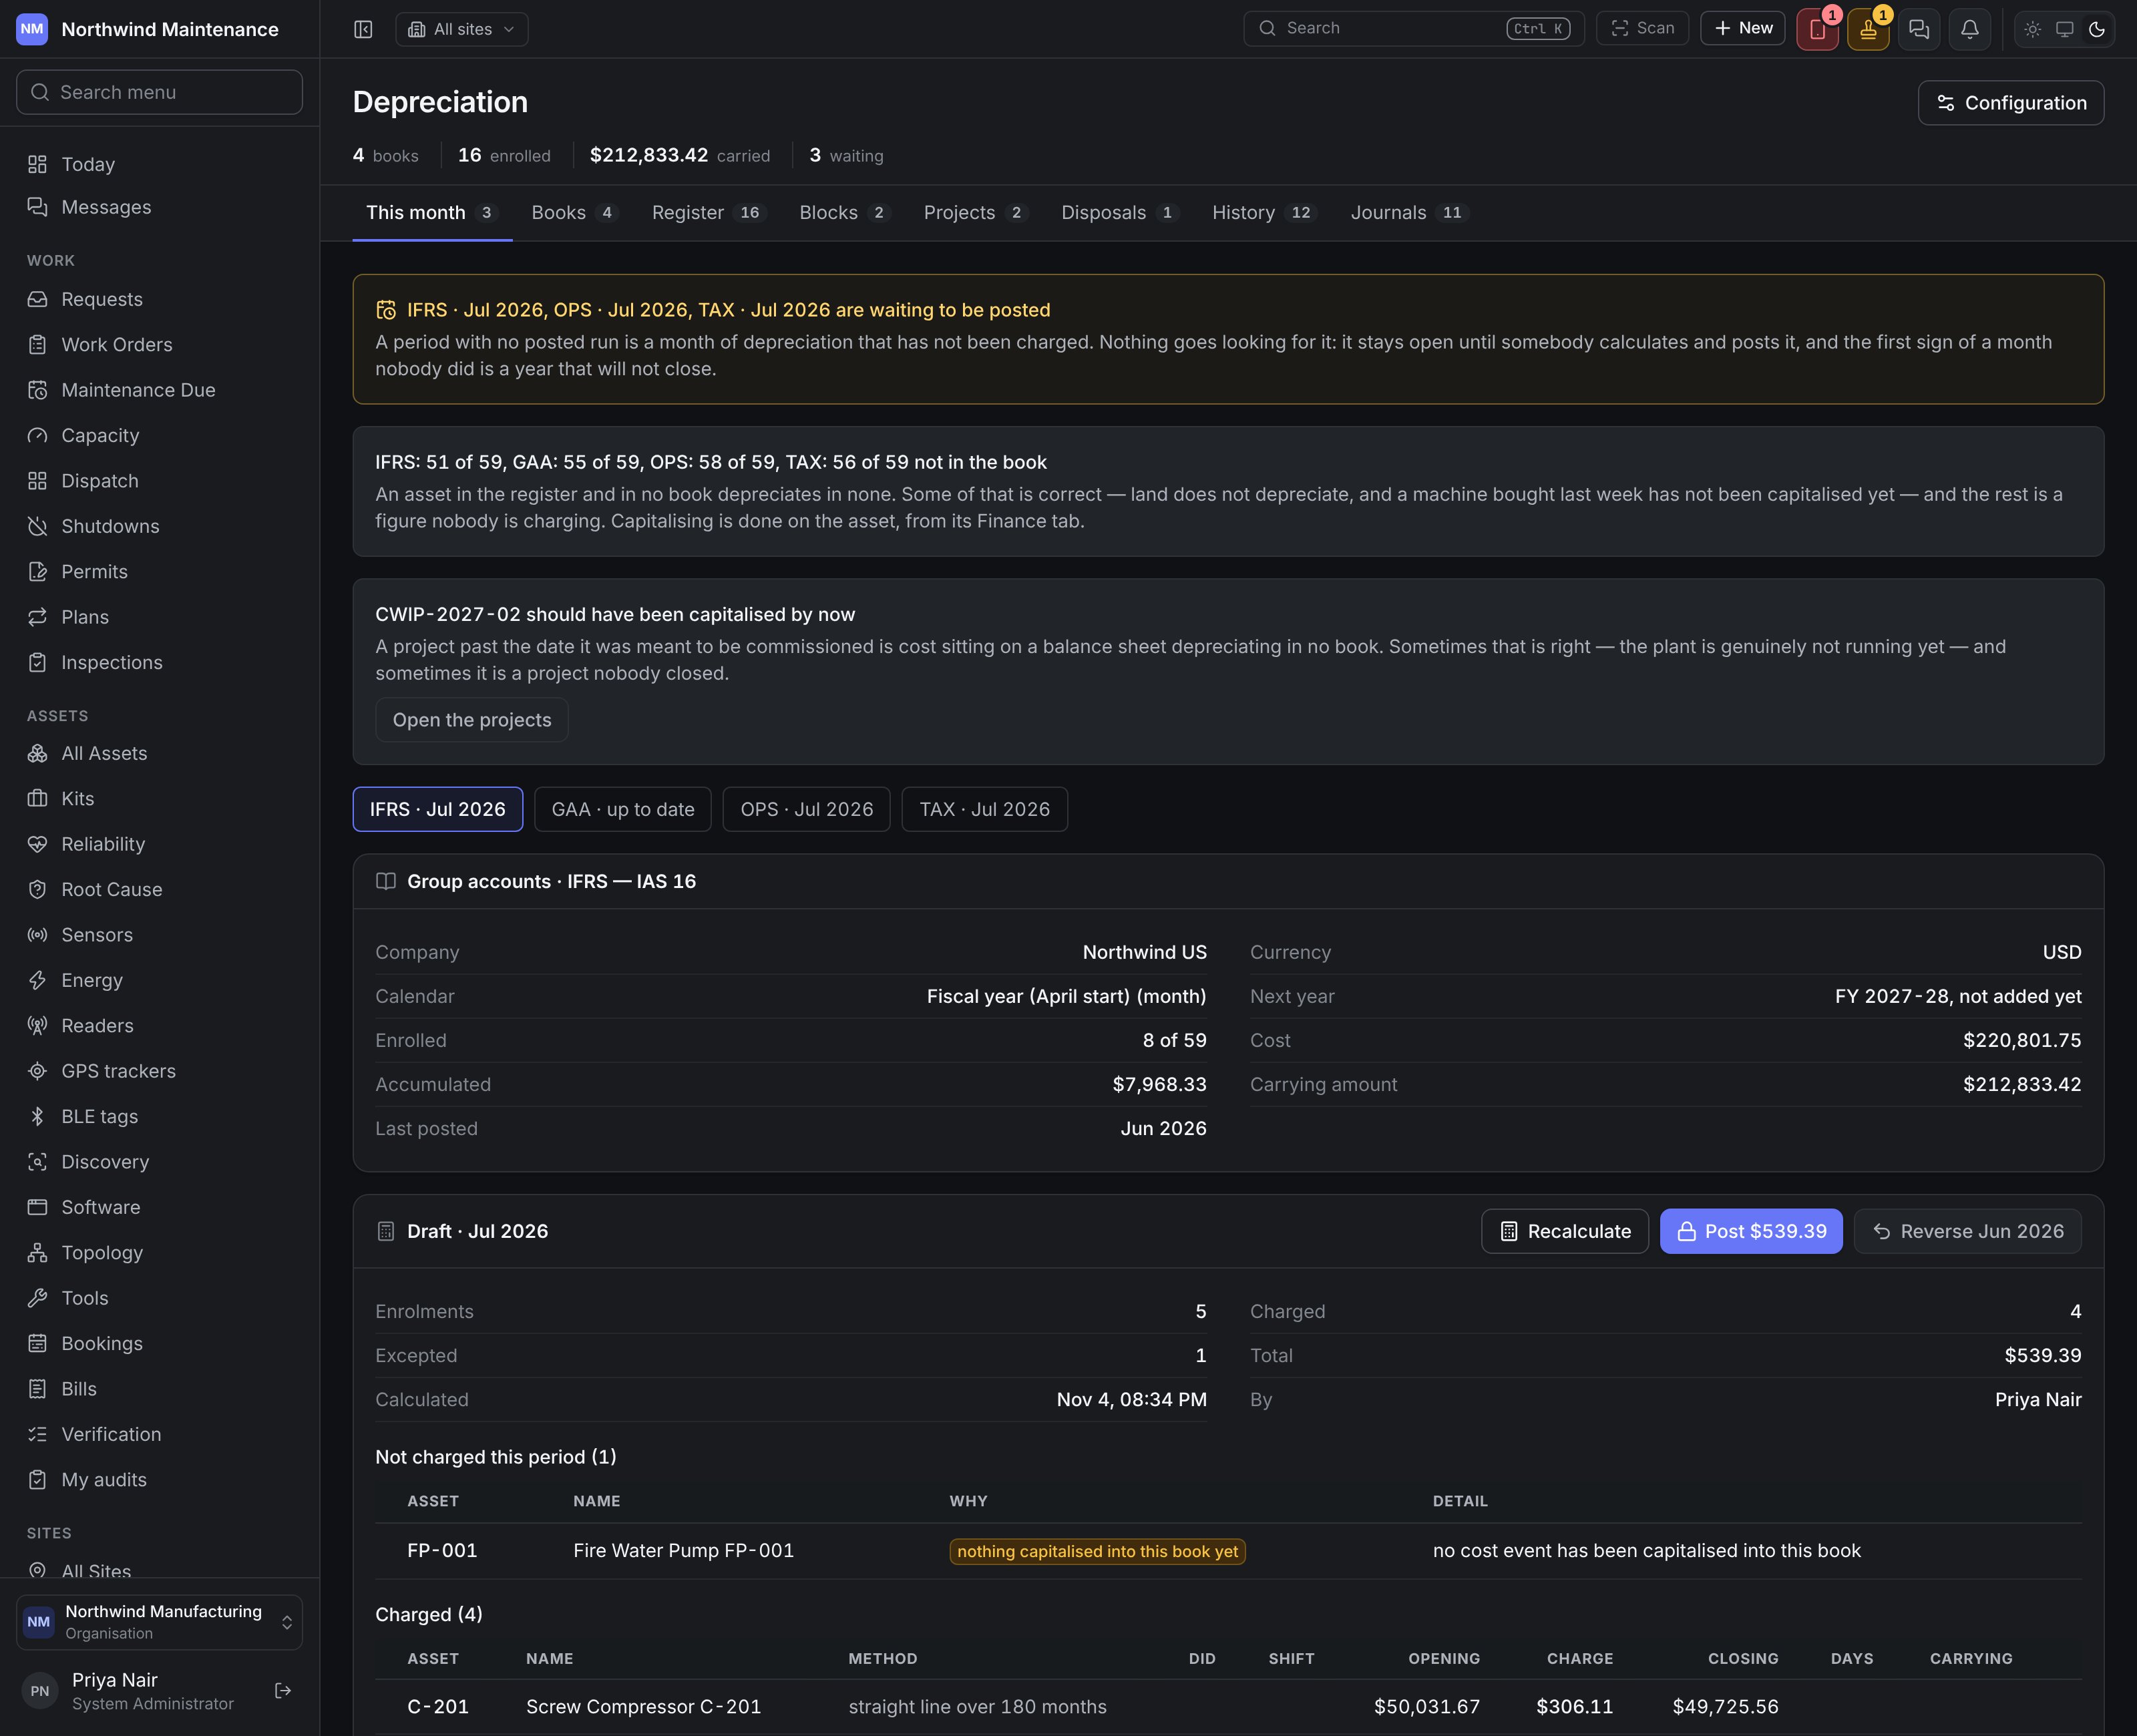
The Depreciation screen on This month: three books waiting to be posted, and a draft run with its exceptions and charges The Depreciation screen on This month: three books waiting to be posted, and a draft run with its exceptions and charges Opening the screen needs View depreciation books, calendars and their rules; somebody without it is told the books are read by finance. Configuration opens depreciation settings — books, calendars, asset classes, policies, rules, ledger accounts and country packs. A new organisation with no book sees Set up depreciation instead.

One asset, several books

Most organisations keep more than one book — typically a statutory book for the accounts and a tax book that computes a deduction — and an enrolled asset is depreciated in all of them at once. The books are expected to disagree: a machine can be fifteen-year straight line in one and inside a 15% written-down-value block in another, in the same month. The product does not pick a winner. Some countries ship a country pack that sets up both books in one step — India’s is described on India: GST and depreciation. A book can be pooled: it depreciates a whole block of similarly rated assets as one written-down value rather than machine by machine. The Blocks tab only appears once a pooled book exists.

Stat strip and banners

books, enrolled (enrolments across all books), carried (total carrying amount) and waiting (books with an open period and nothing posted).

This month

One chip per book, showing its next period (or up to date). Choose a book to see its card: Company, Currency, Calendar (the calendar of the year the book is in now), Next year, Enrolled, Cost, Accumulated, Carrying amount and Last posted. A fiscal calendar is one financial year. A book keeps the calendar it was set up on and runs on into each calendar that Continues it, so Next year names the calendar its months go on into, or says the year is not added yet. When every period of the book’s financial year has been posted, the card says so, and that the book carries on into the next year once a fiscal calendar for that year is added, continuing the current one. A book whose calendar has no periods says This book has no periods. The draft shows Enrolments, Charged, Excepted, Total, when it was Calculated and By whom. Not charged this period is read first: Charged lists each asset with Method, Did (measured work, for units-of-production), Shift (a multi-shift factor such as ×1.5, with how many hours it ran against the site’s normal), Opening, Charge, Closing, Days and Carrying.

Books
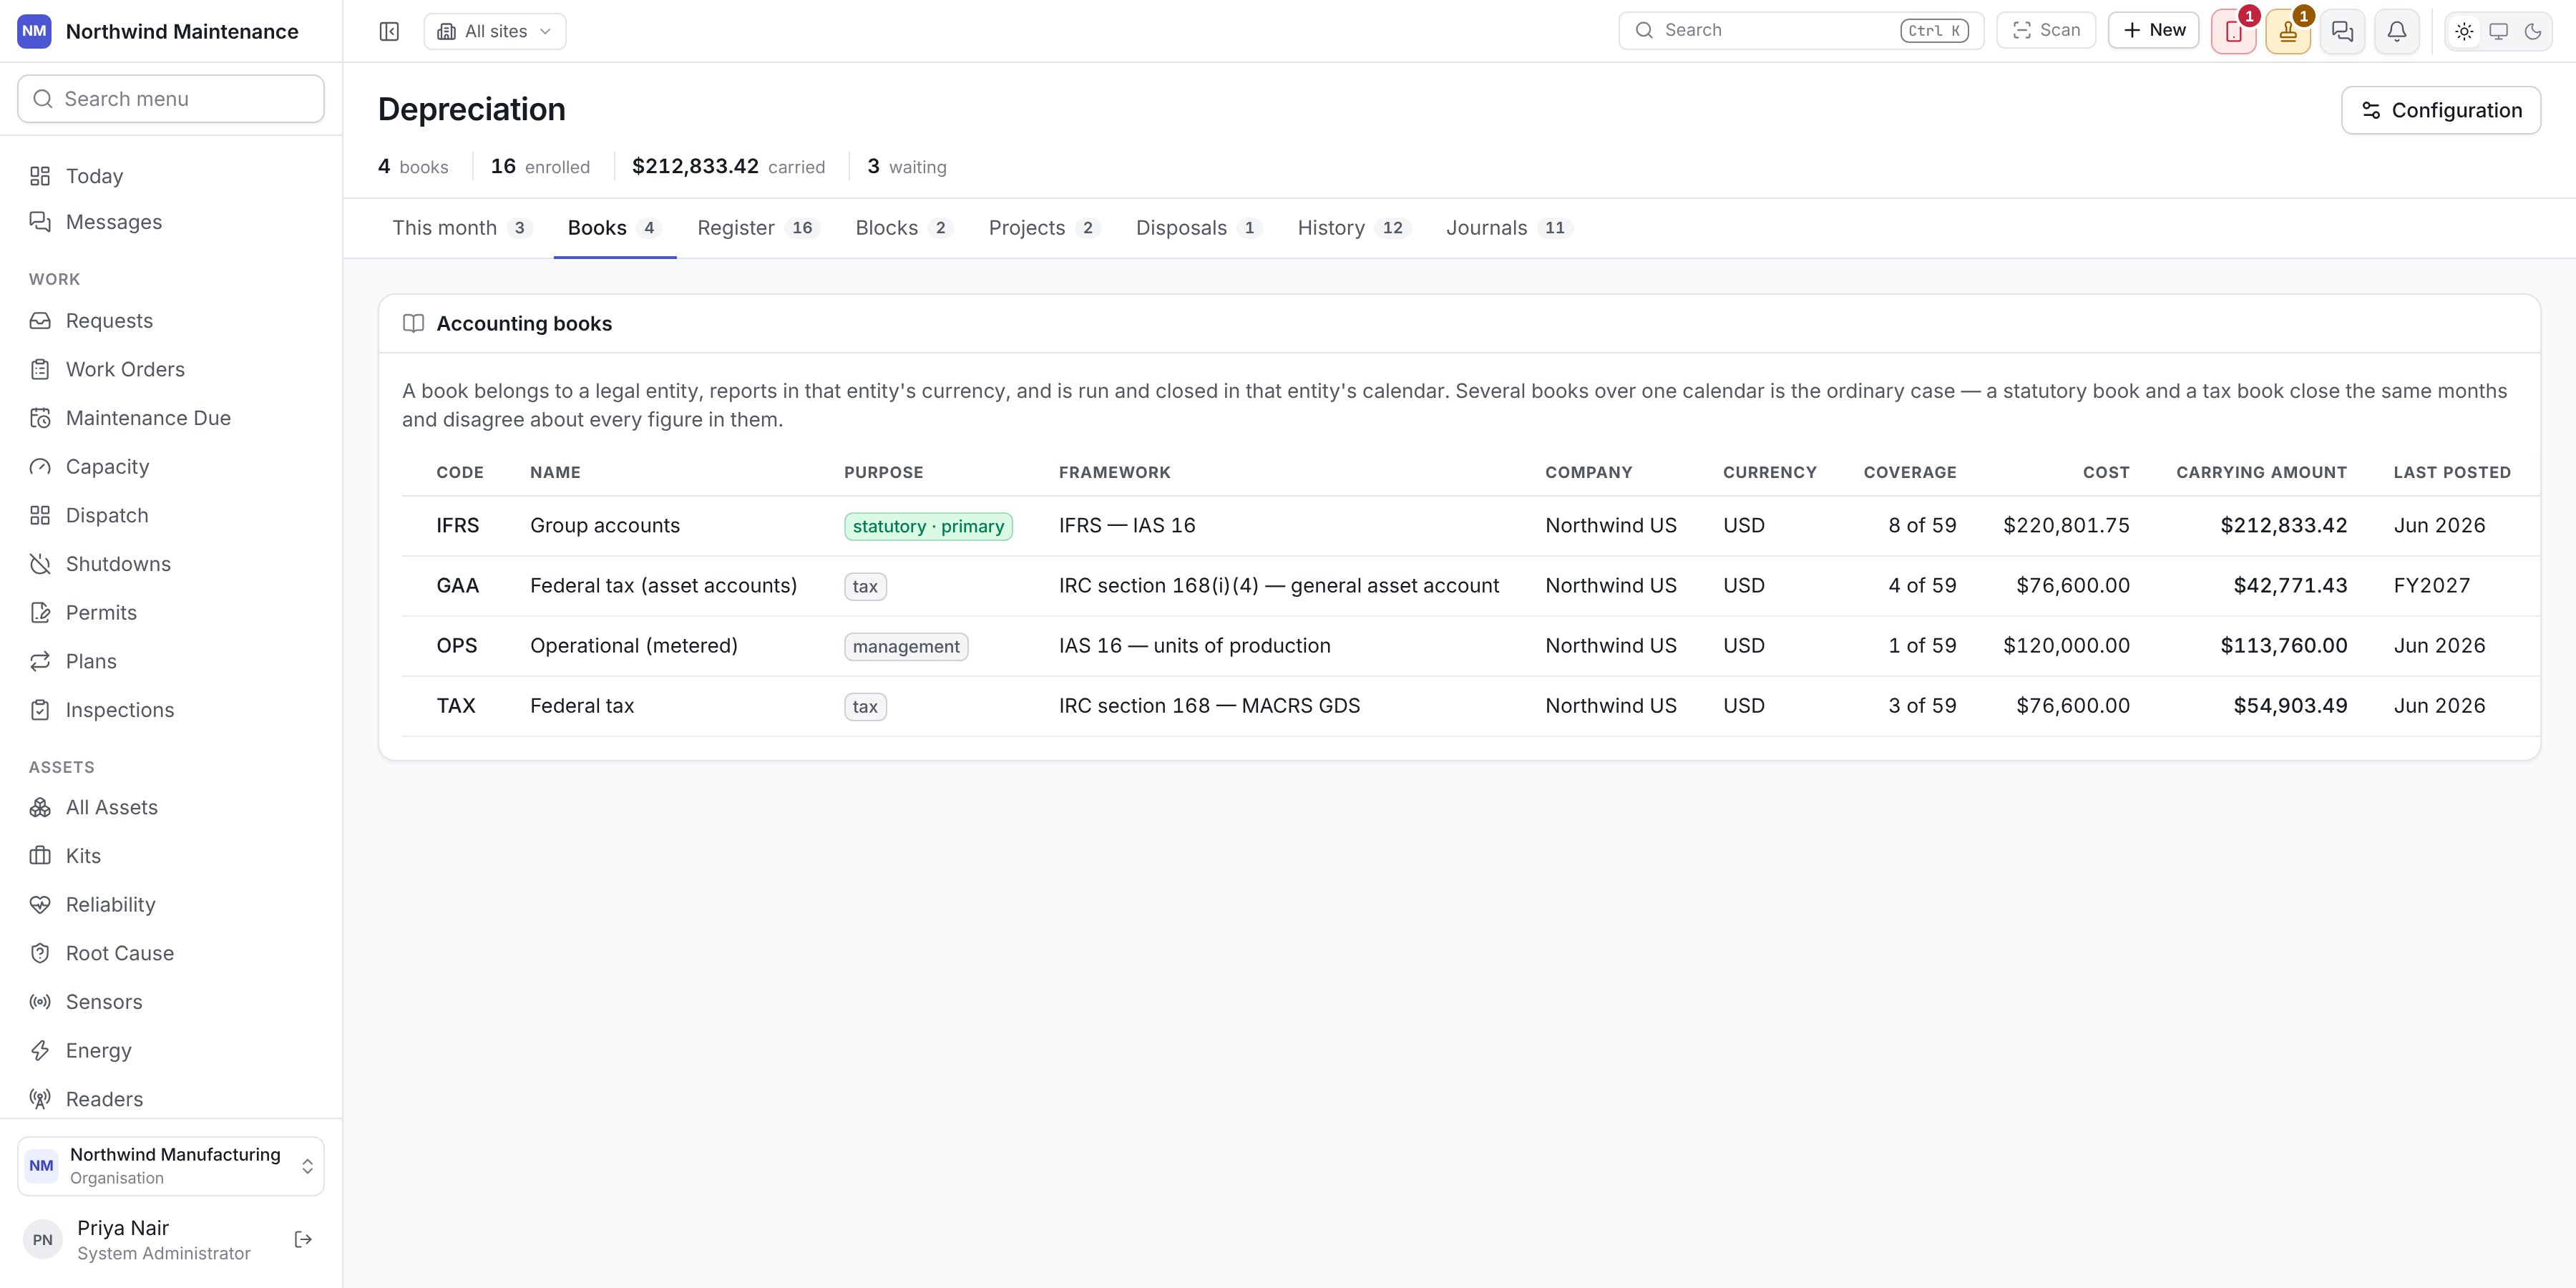
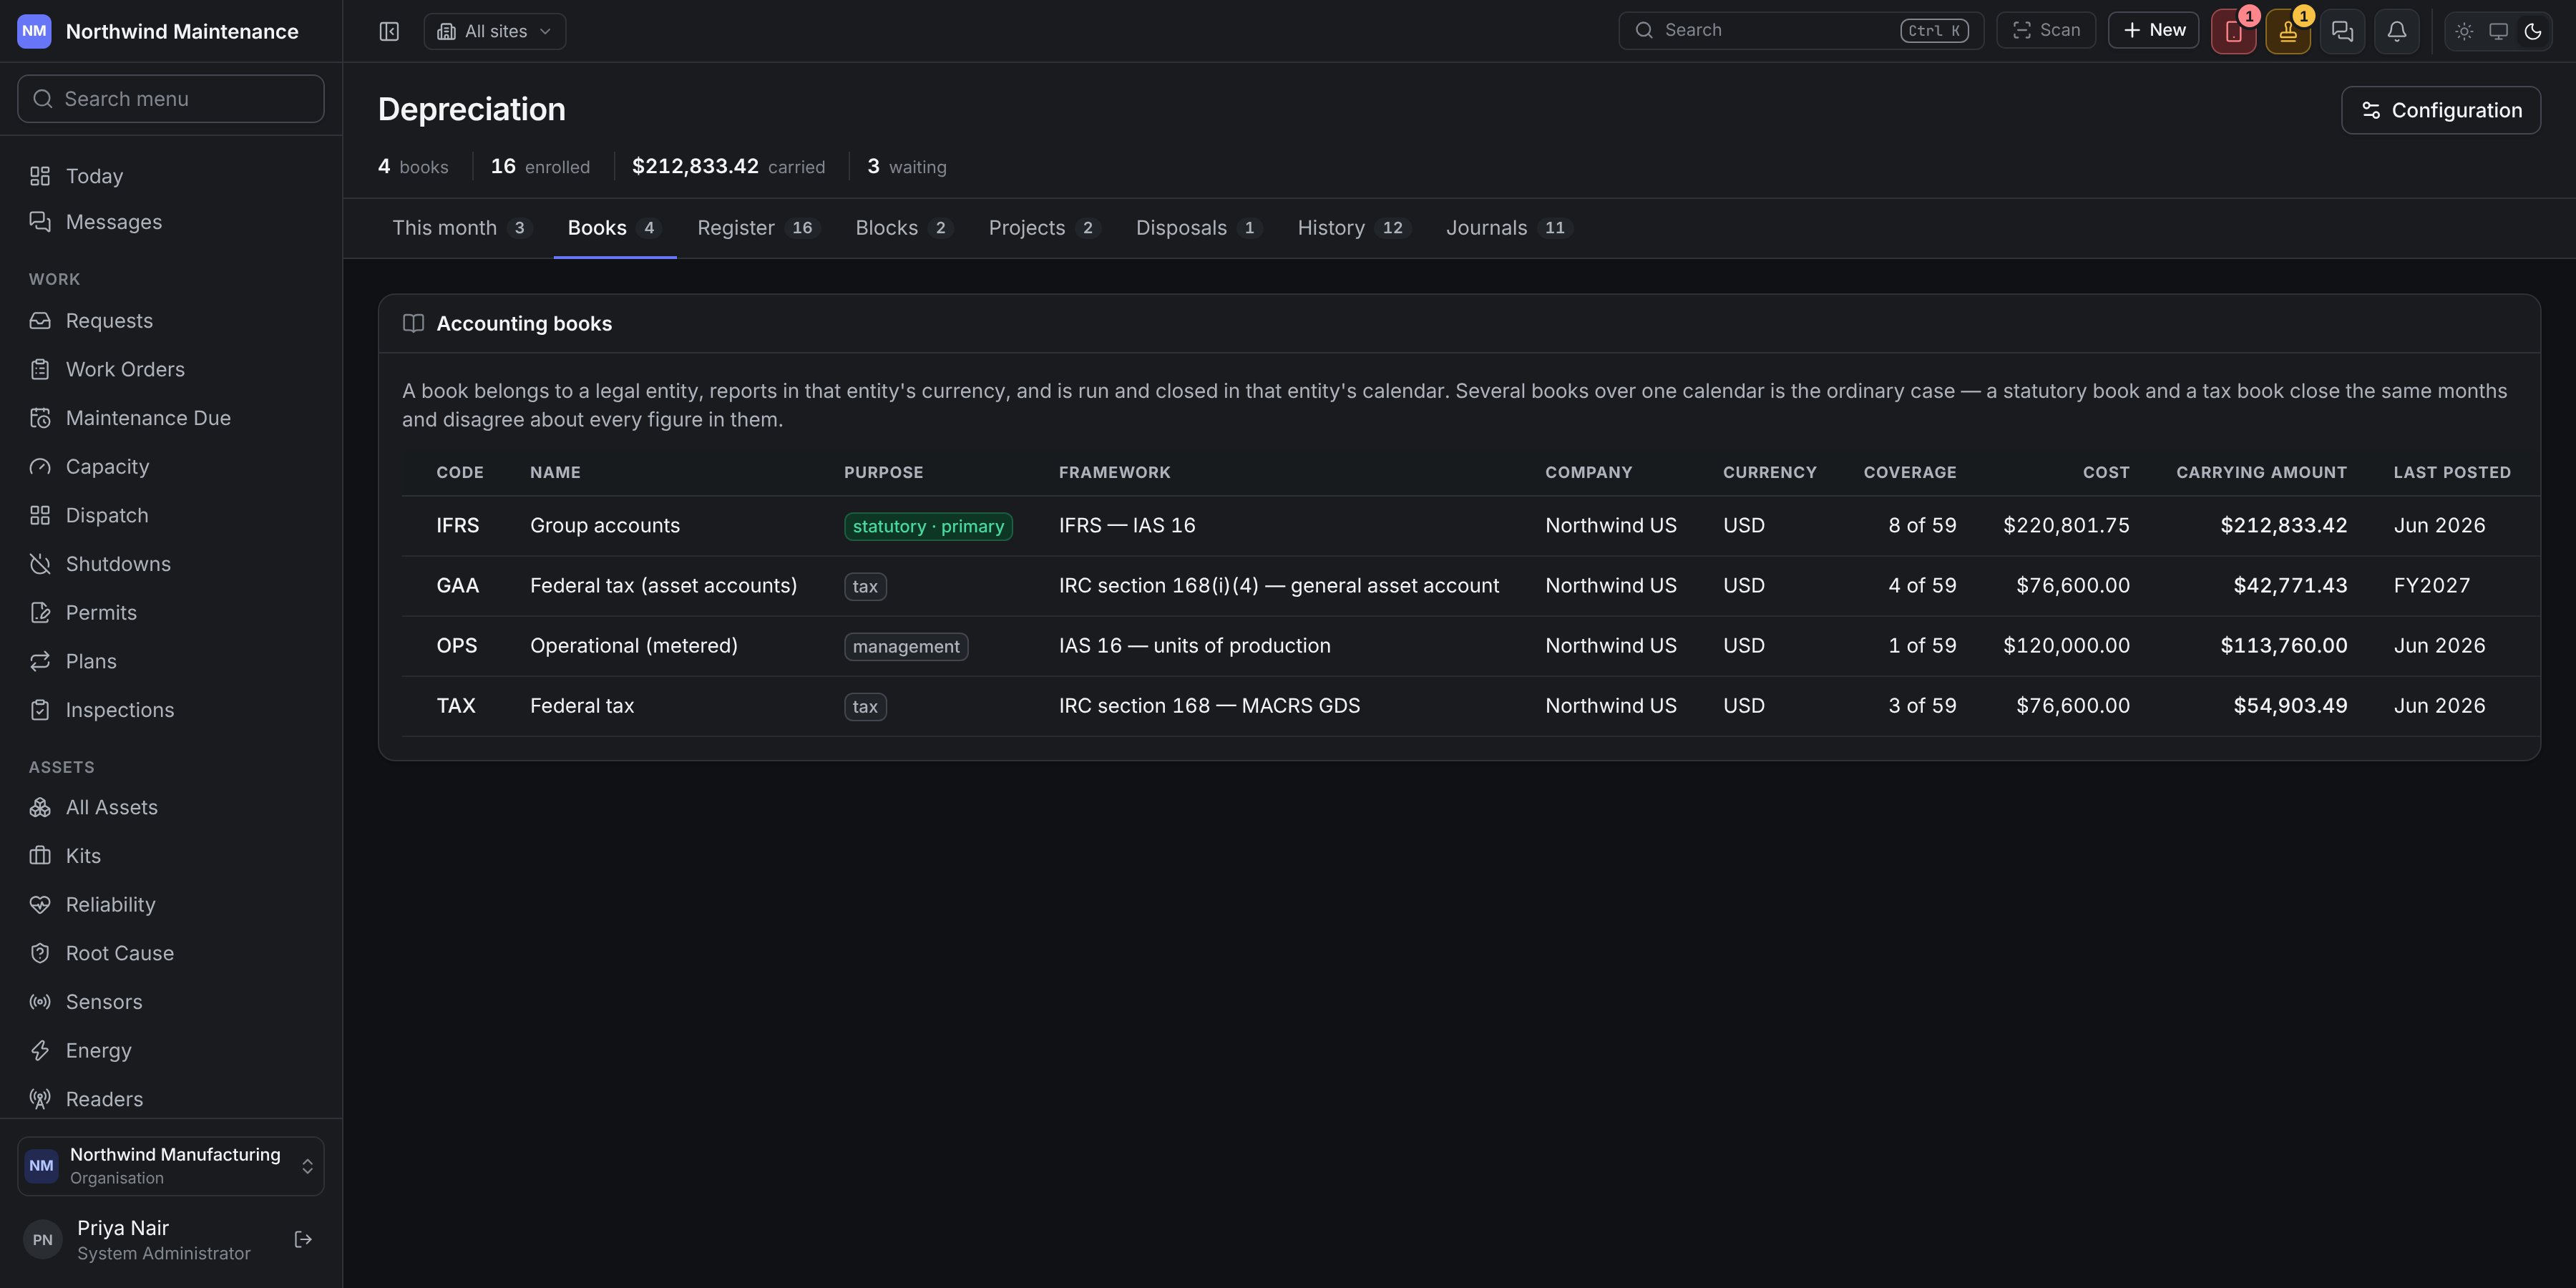
The Books tab, with four books and their coverage, cost and carrying amount The Books tab, with four books and their coverage, cost and carrying amount Accounting books: Code, Name, Purpose (statutory, tax, management — one marked primary), Framework, Company, Currency, Coverage (assets in the book out of the register), Cost, Carrying amount, Last posted, Open period, and Journal (mapped or no posting rule). A book belongs to one legal entity, its currency and its calendar.

Register

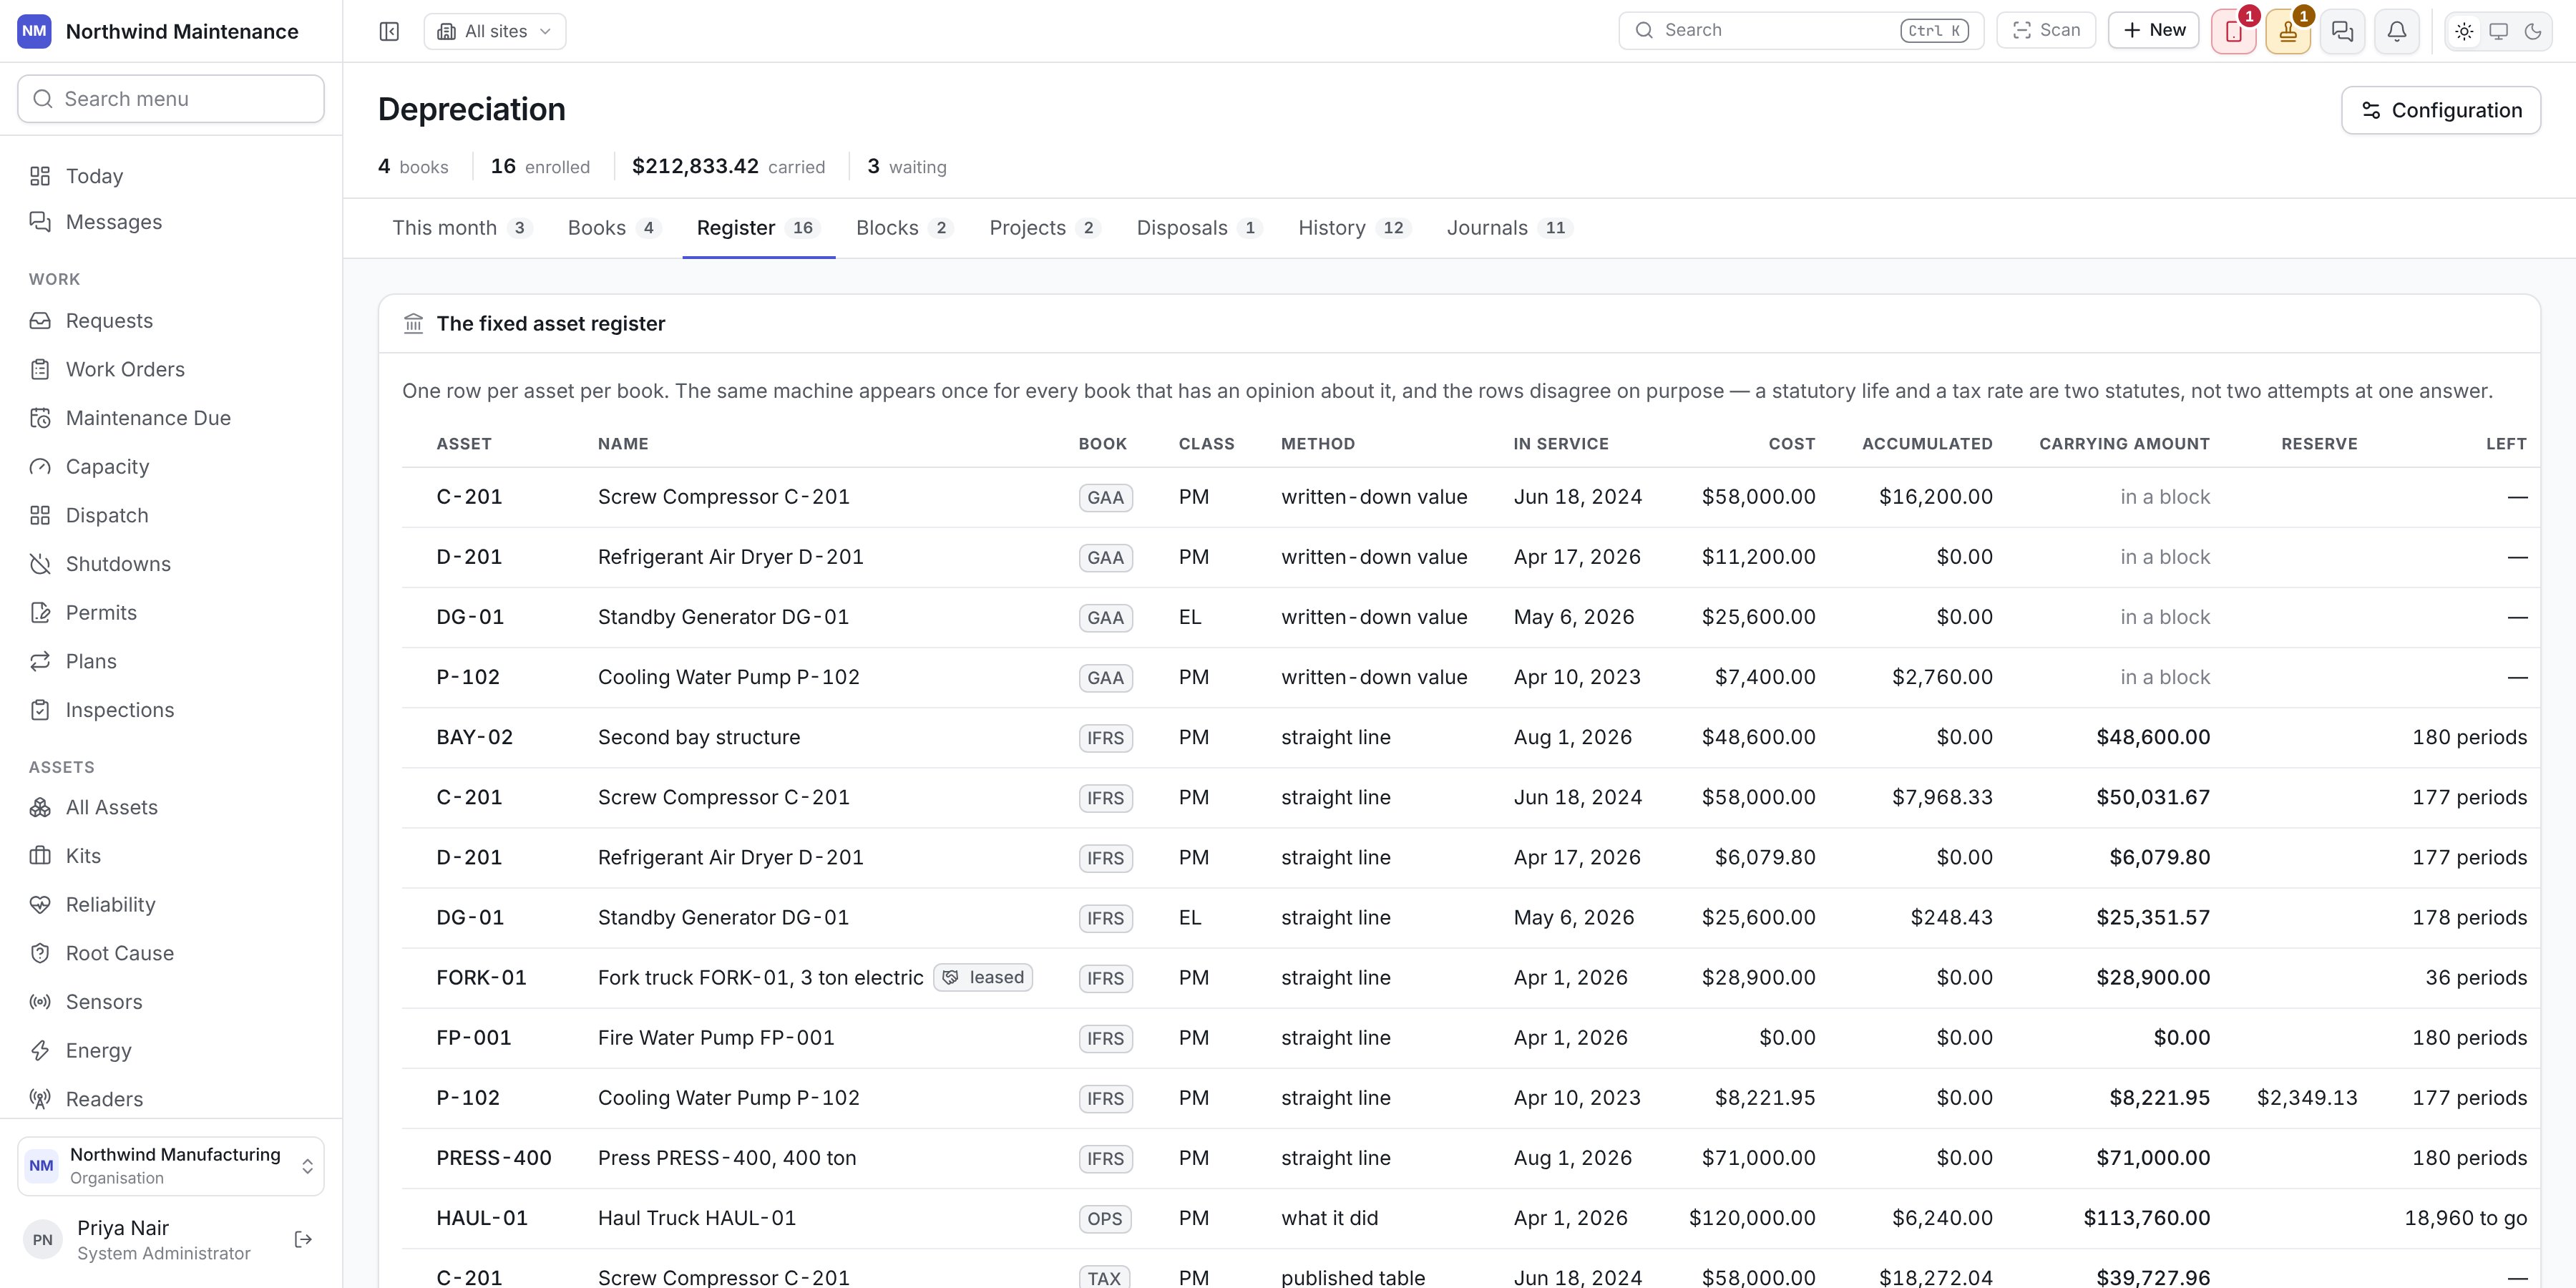
The fixed asset register: one row per asset per book The fixed asset register: one row per asset per book The fixed asset register has one row per asset per book: Asset, Name (tagged leased where relevant), Book, Class, Method, In service, Cost, Accumulated, Carrying amount (in a block for a pooled book), Reserve (revaluation reserve), Left (periods of life remaining) and State (active, written down, disposed). An asset enters a book by being capitalised from its own Finance tab. Viewing needs View the fixed asset register and its carrying amounts.

Blocks

For a pooled book, one row per block per year: Book, Block, Year, Rate, Assets, Opening, Added, full rate, Added, half rate (in use for fewer than 180 days of the year, so half the rate applies), Proceeds out, Depreciation, Excess proceeds (more received than the block held — the block goes to nil and the excess is a capital gain for the tax return) and Closing. Each year opens where the last one closed. See the India example.

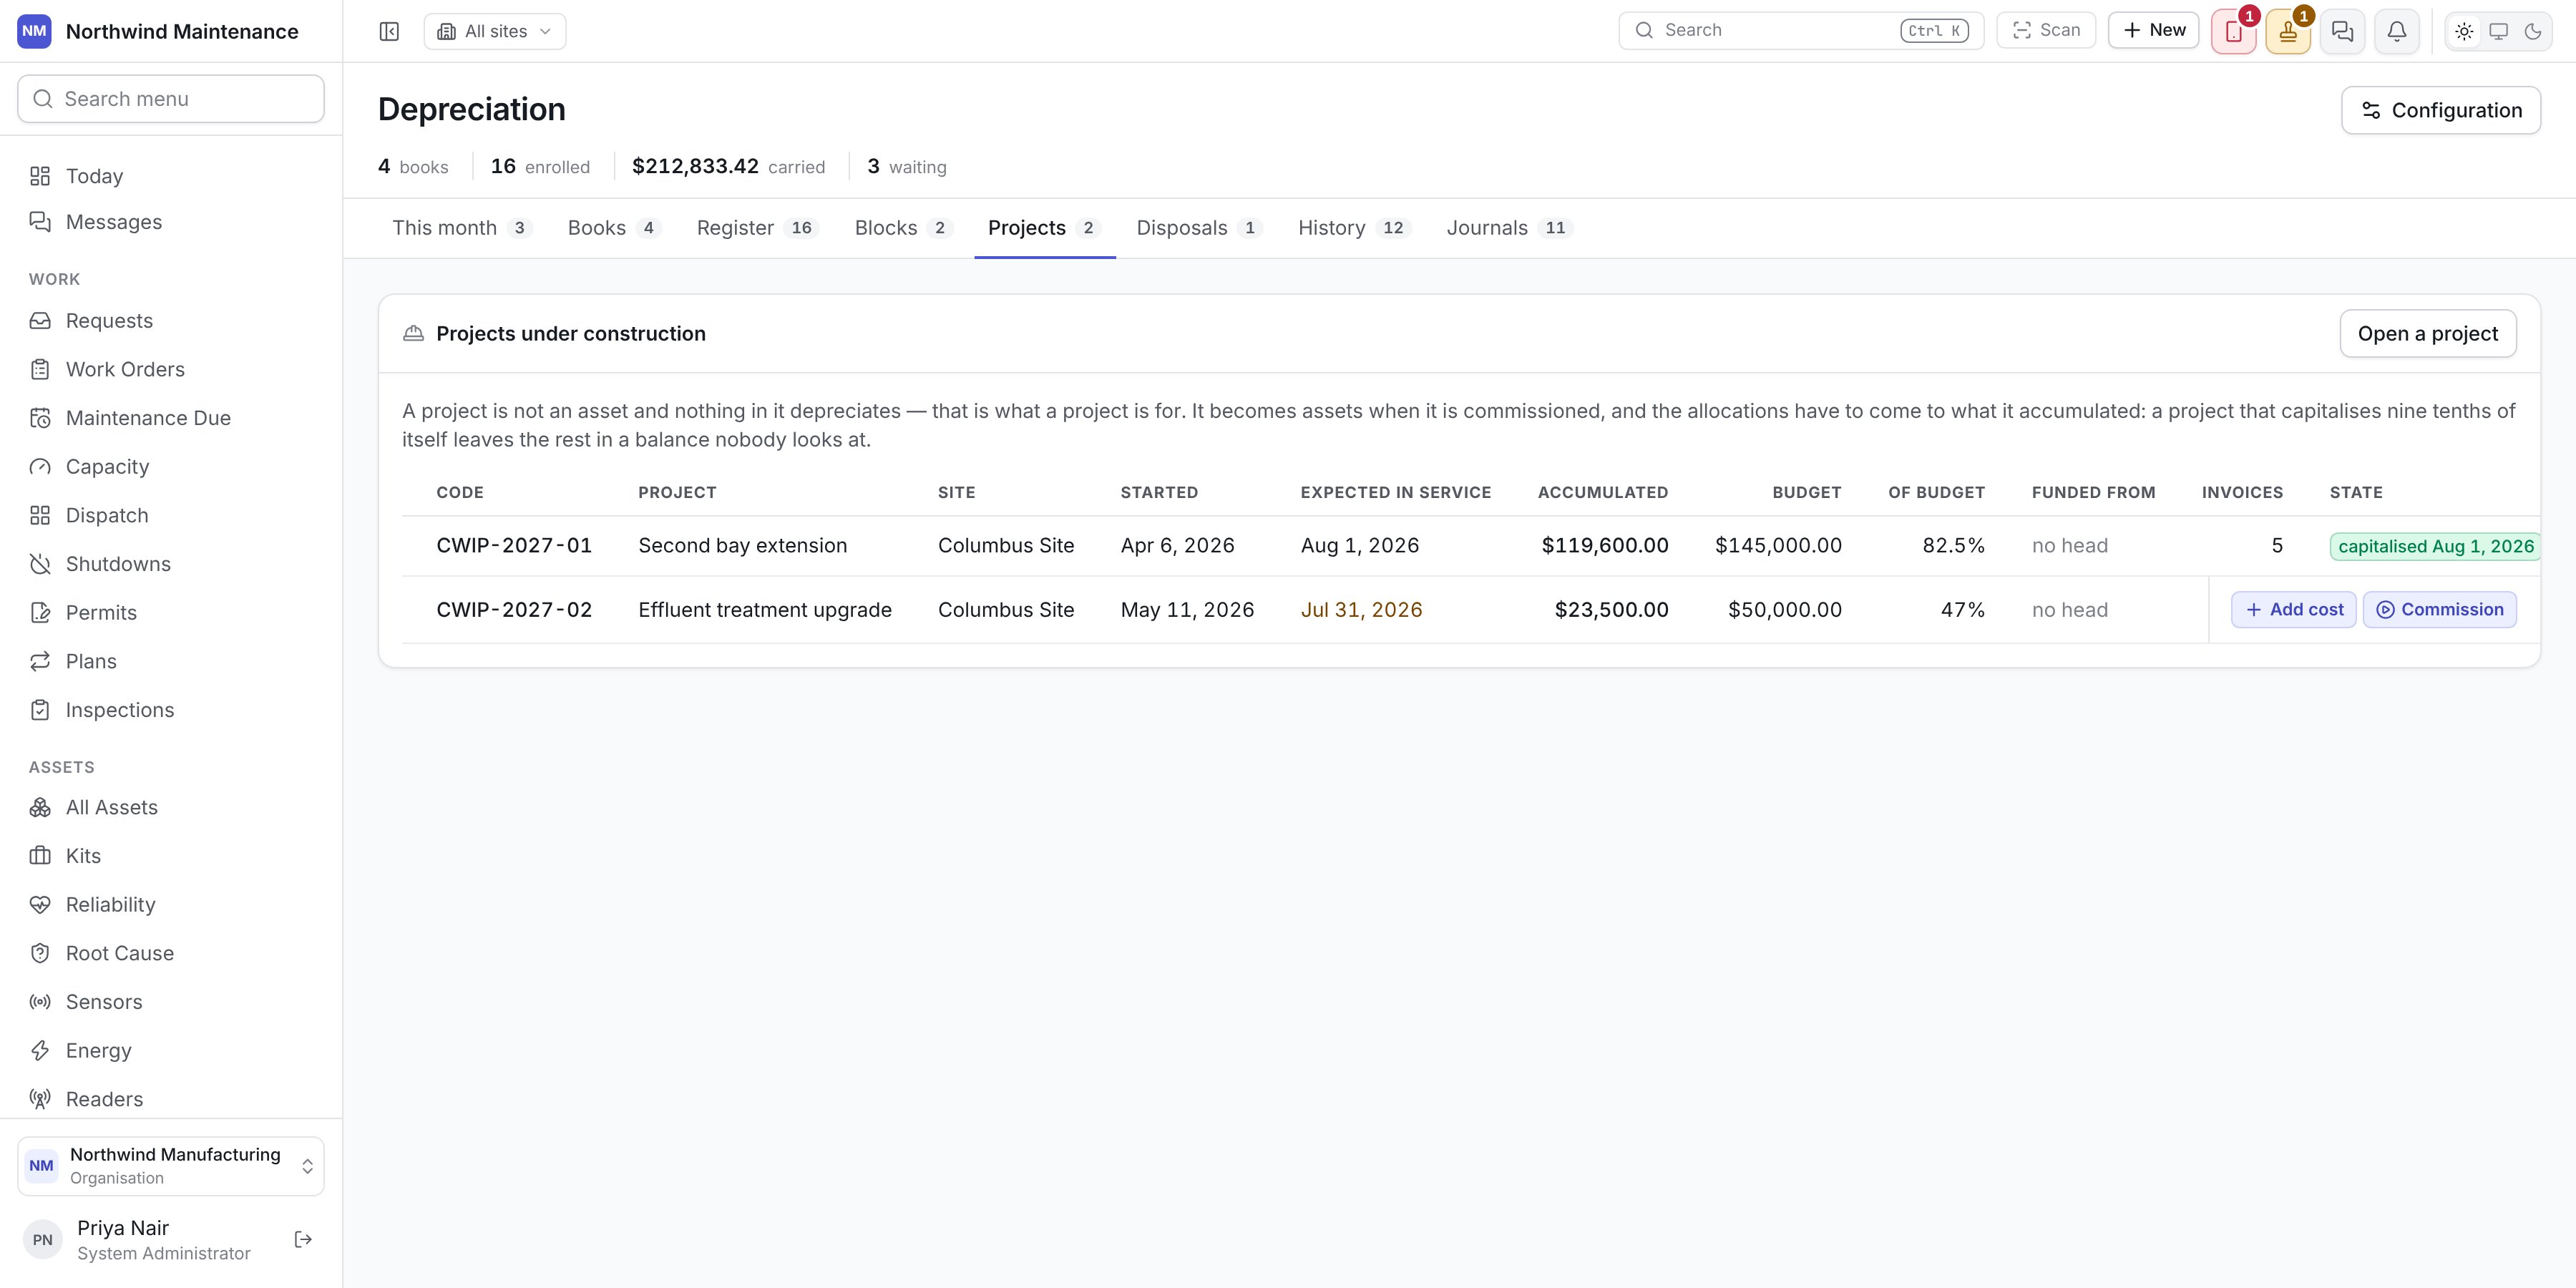
Projects

Projects under construction, with accumulated cost against budget Projects under construction, with accumulated cost against budget Projects under construction hold the cost of something being built — capital work in progress — so it is not on the register pretending to be plant. Nothing in a project depreciates. Columns: Code, Project, Site, Started, Expected in service, Accumulated, Budget, Of budget, Funded from (a budget head, or no head), Invoices and State (overdue, capitalised).

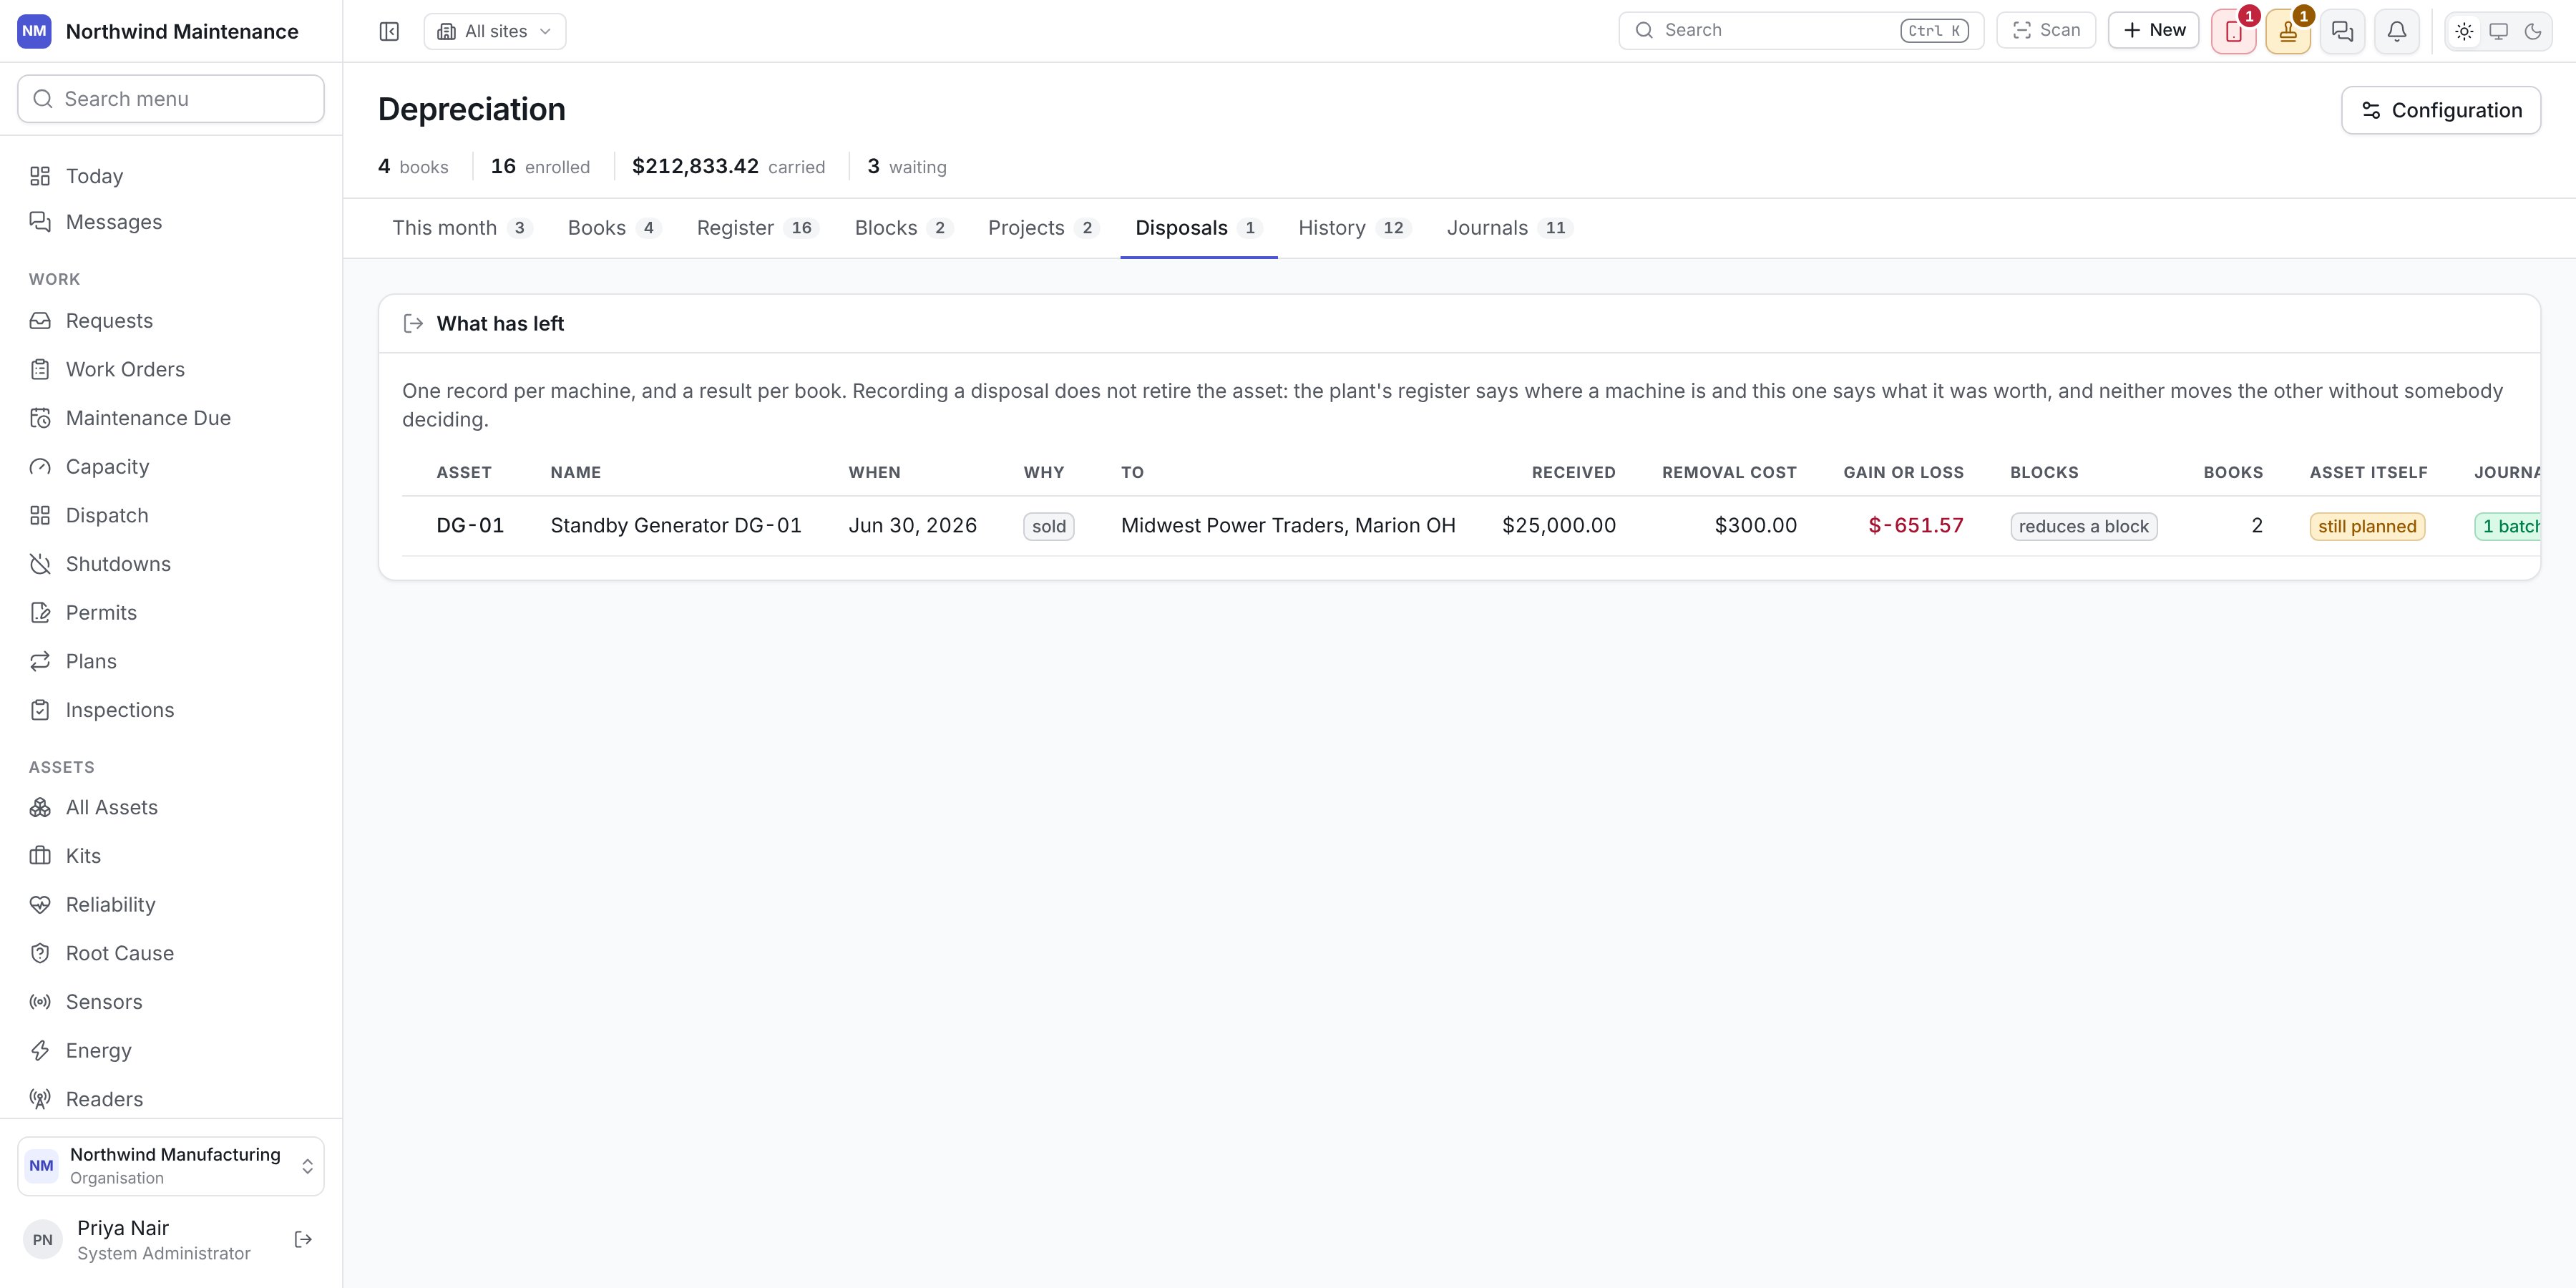
Disposals

What has left: a disposed asset with its result per book What has left: a disposed asset with its result per book What has left — one record per machine and a result per book: Asset, Name, When, Why, To, Received, Removal cost, Gain or loss (or none per asset for a pooled book), Blocks (reduces a block), Books, Asset itself (whether the asset record is still active — recording a disposal does not retire the asset) and Journal (no entry yet, none needed, or a batch). Build the entry creates the disposal journal once the accounts are mapped. A disposal is recorded with Dispose on the asset’s Finance tab, after the period it falls in has been posted; it ends depreciation in every book. The form asks once, at the top, why the asset left, who took it and the reference — and for a sale, the buyer (a customer or a supplier), the invoice number and date and the price each asset went for — so the same answers serve every book. Left, but still carried lists assets gone with no disposal recorded.

History

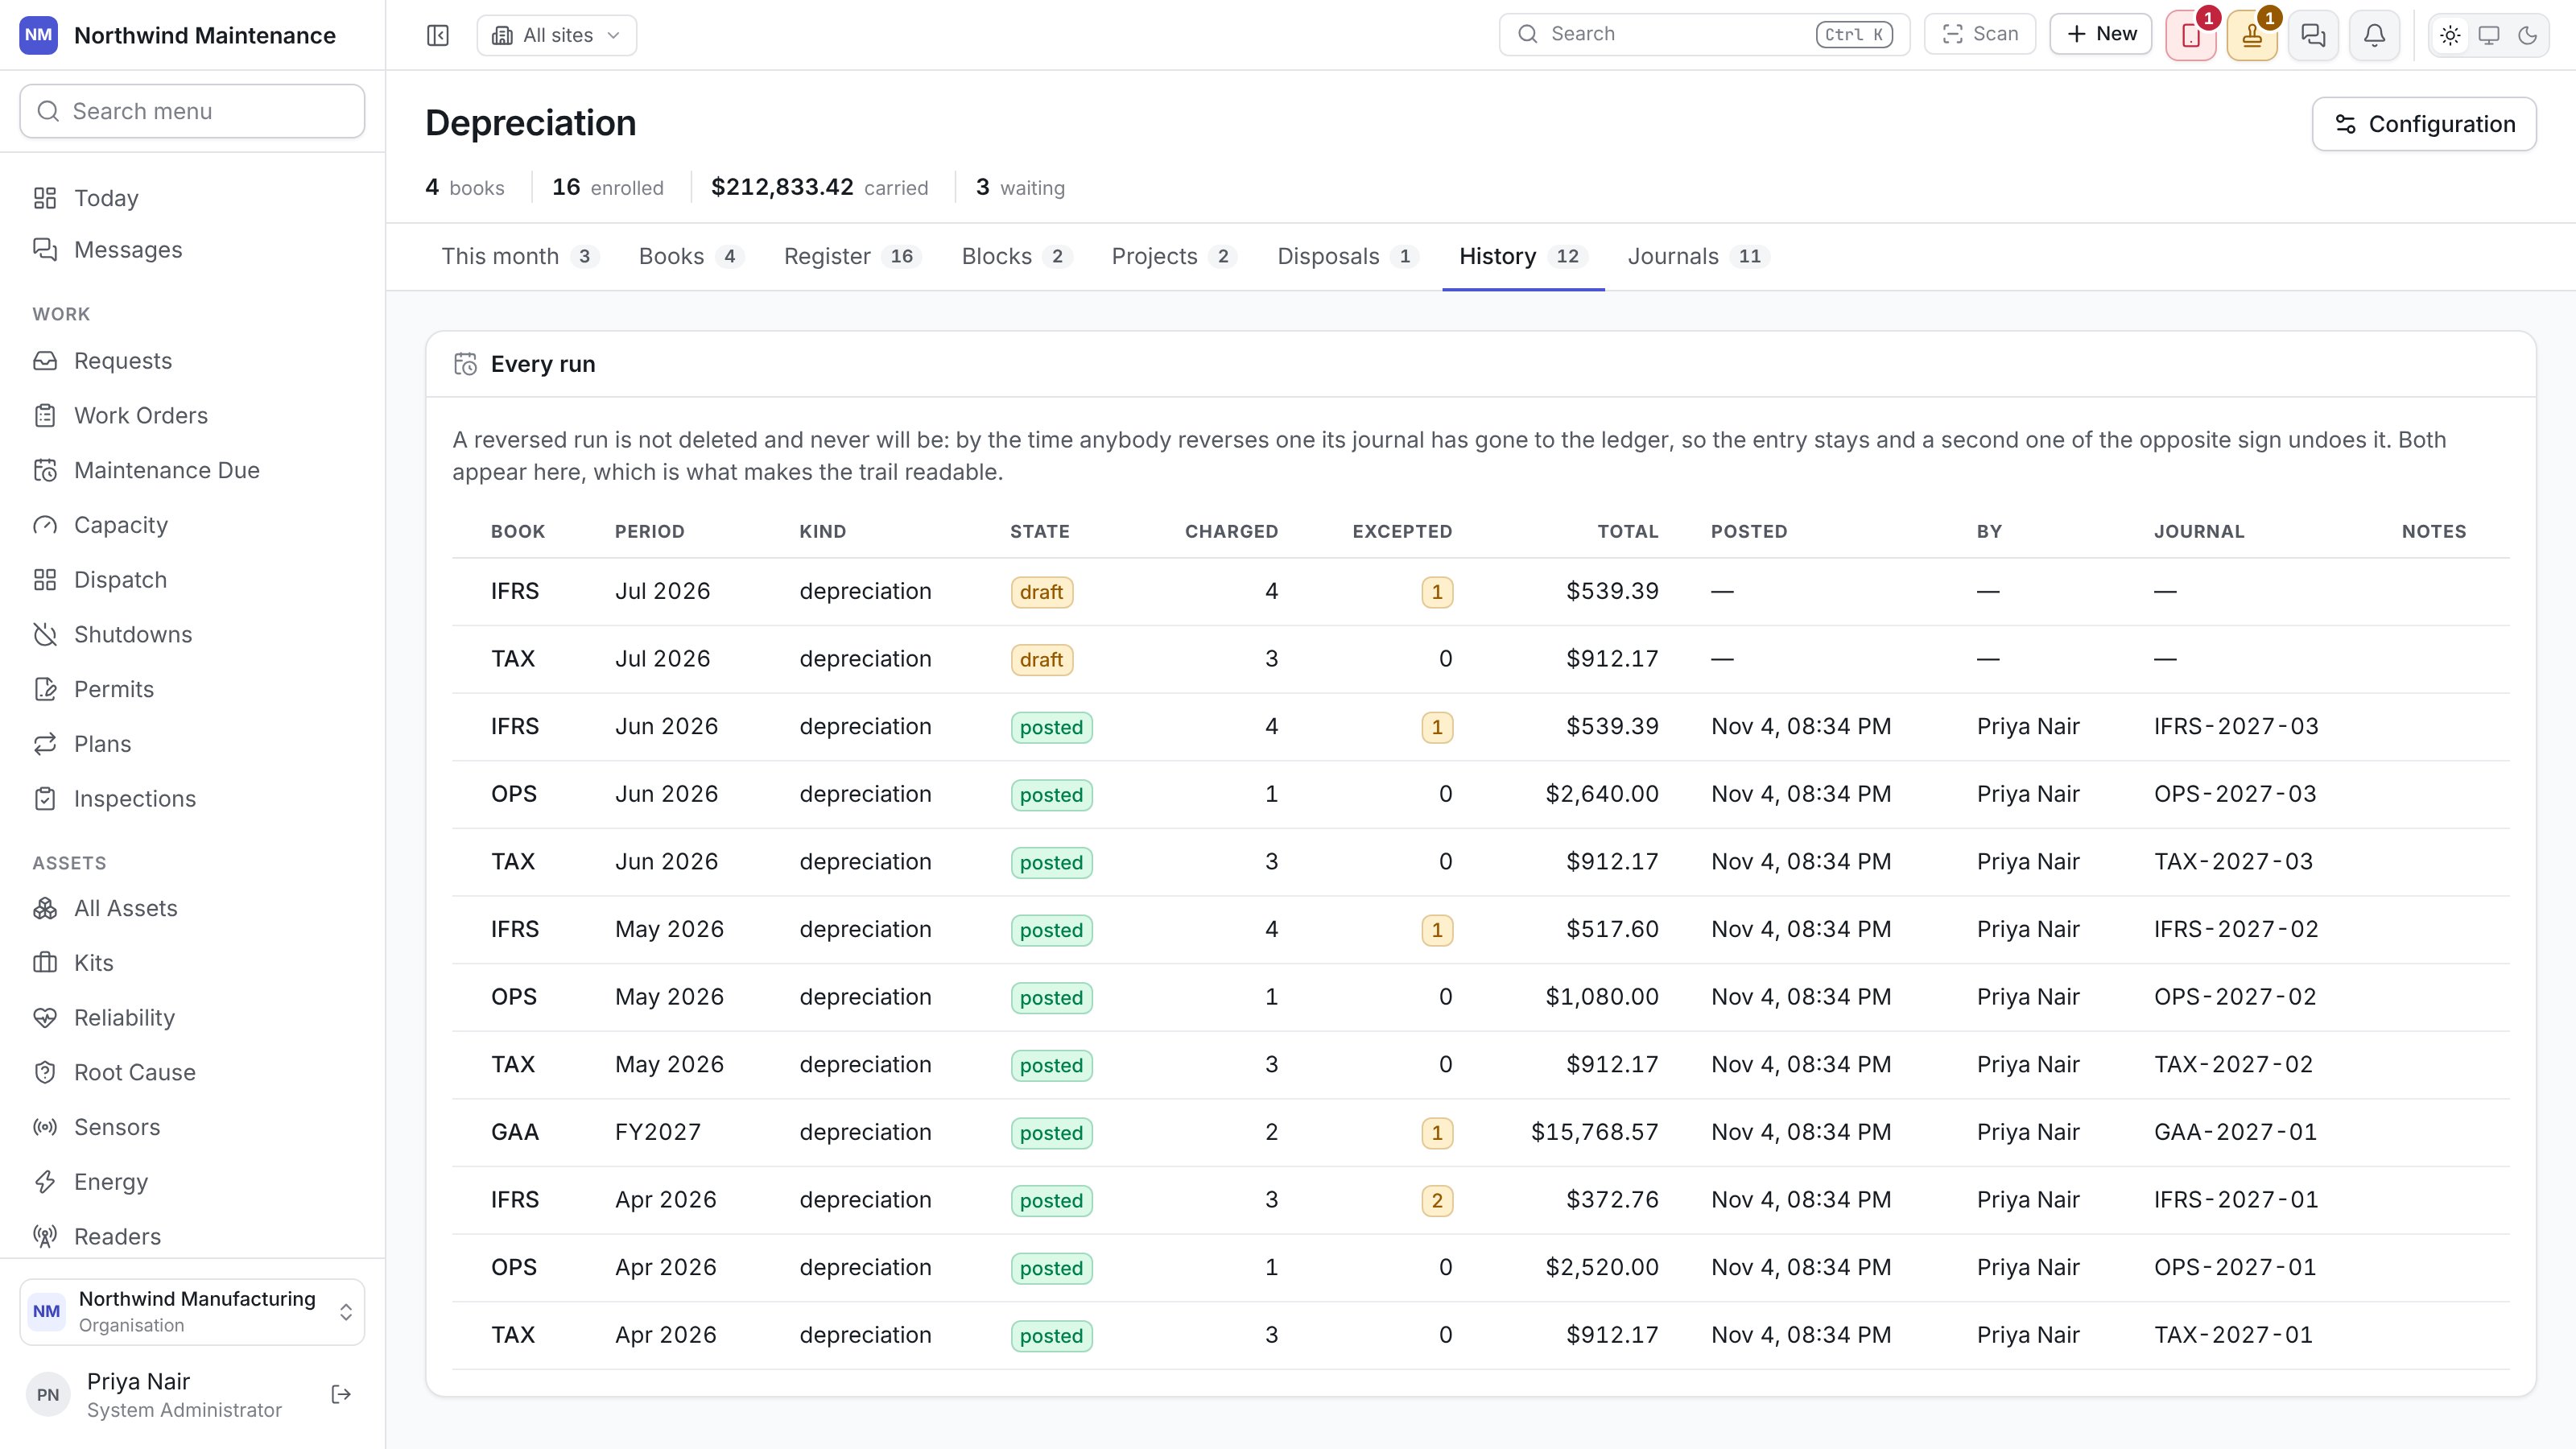
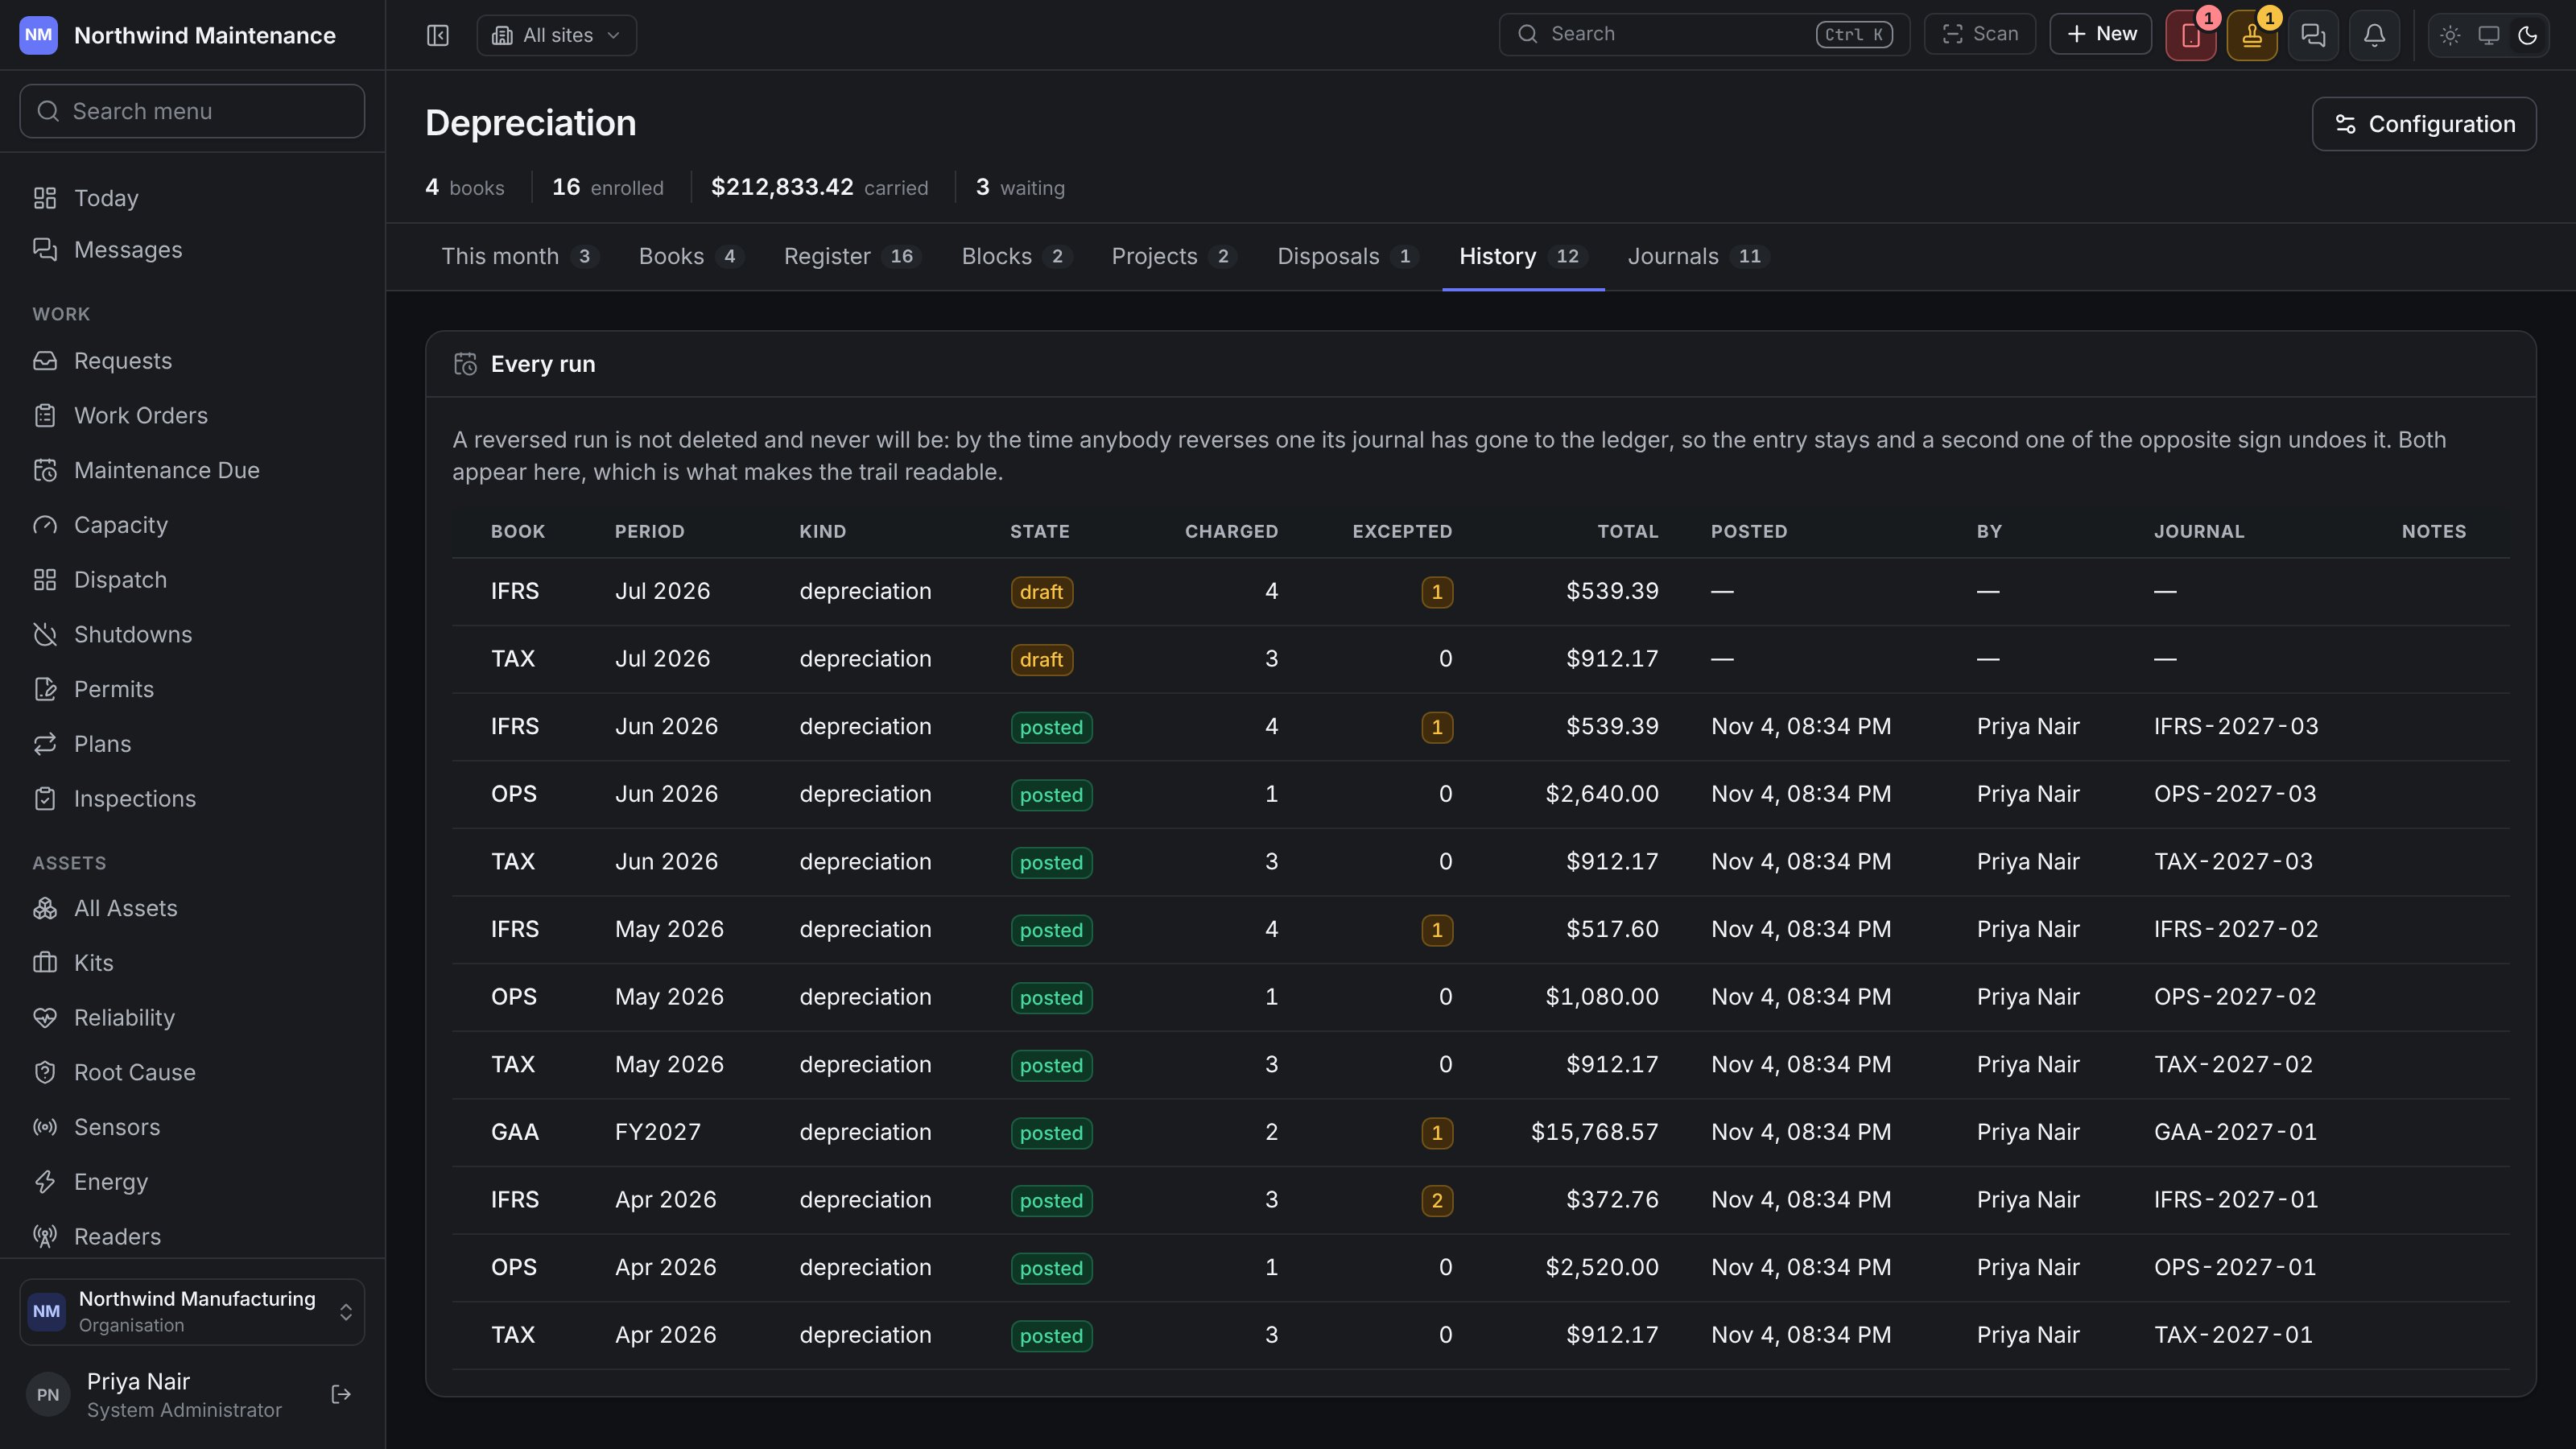
Every run, posted or not: Book, Period, Kind, State (draft, posted, reversed), Charged, Excepted, Total, Posted, By, Journal and Notes. A reversed run is never deleted; its reversal appears beside it. Every depreciation run, drafts and posted, with the journal each produced Every depreciation run, drafts and posted, with the journal each produced
Journals

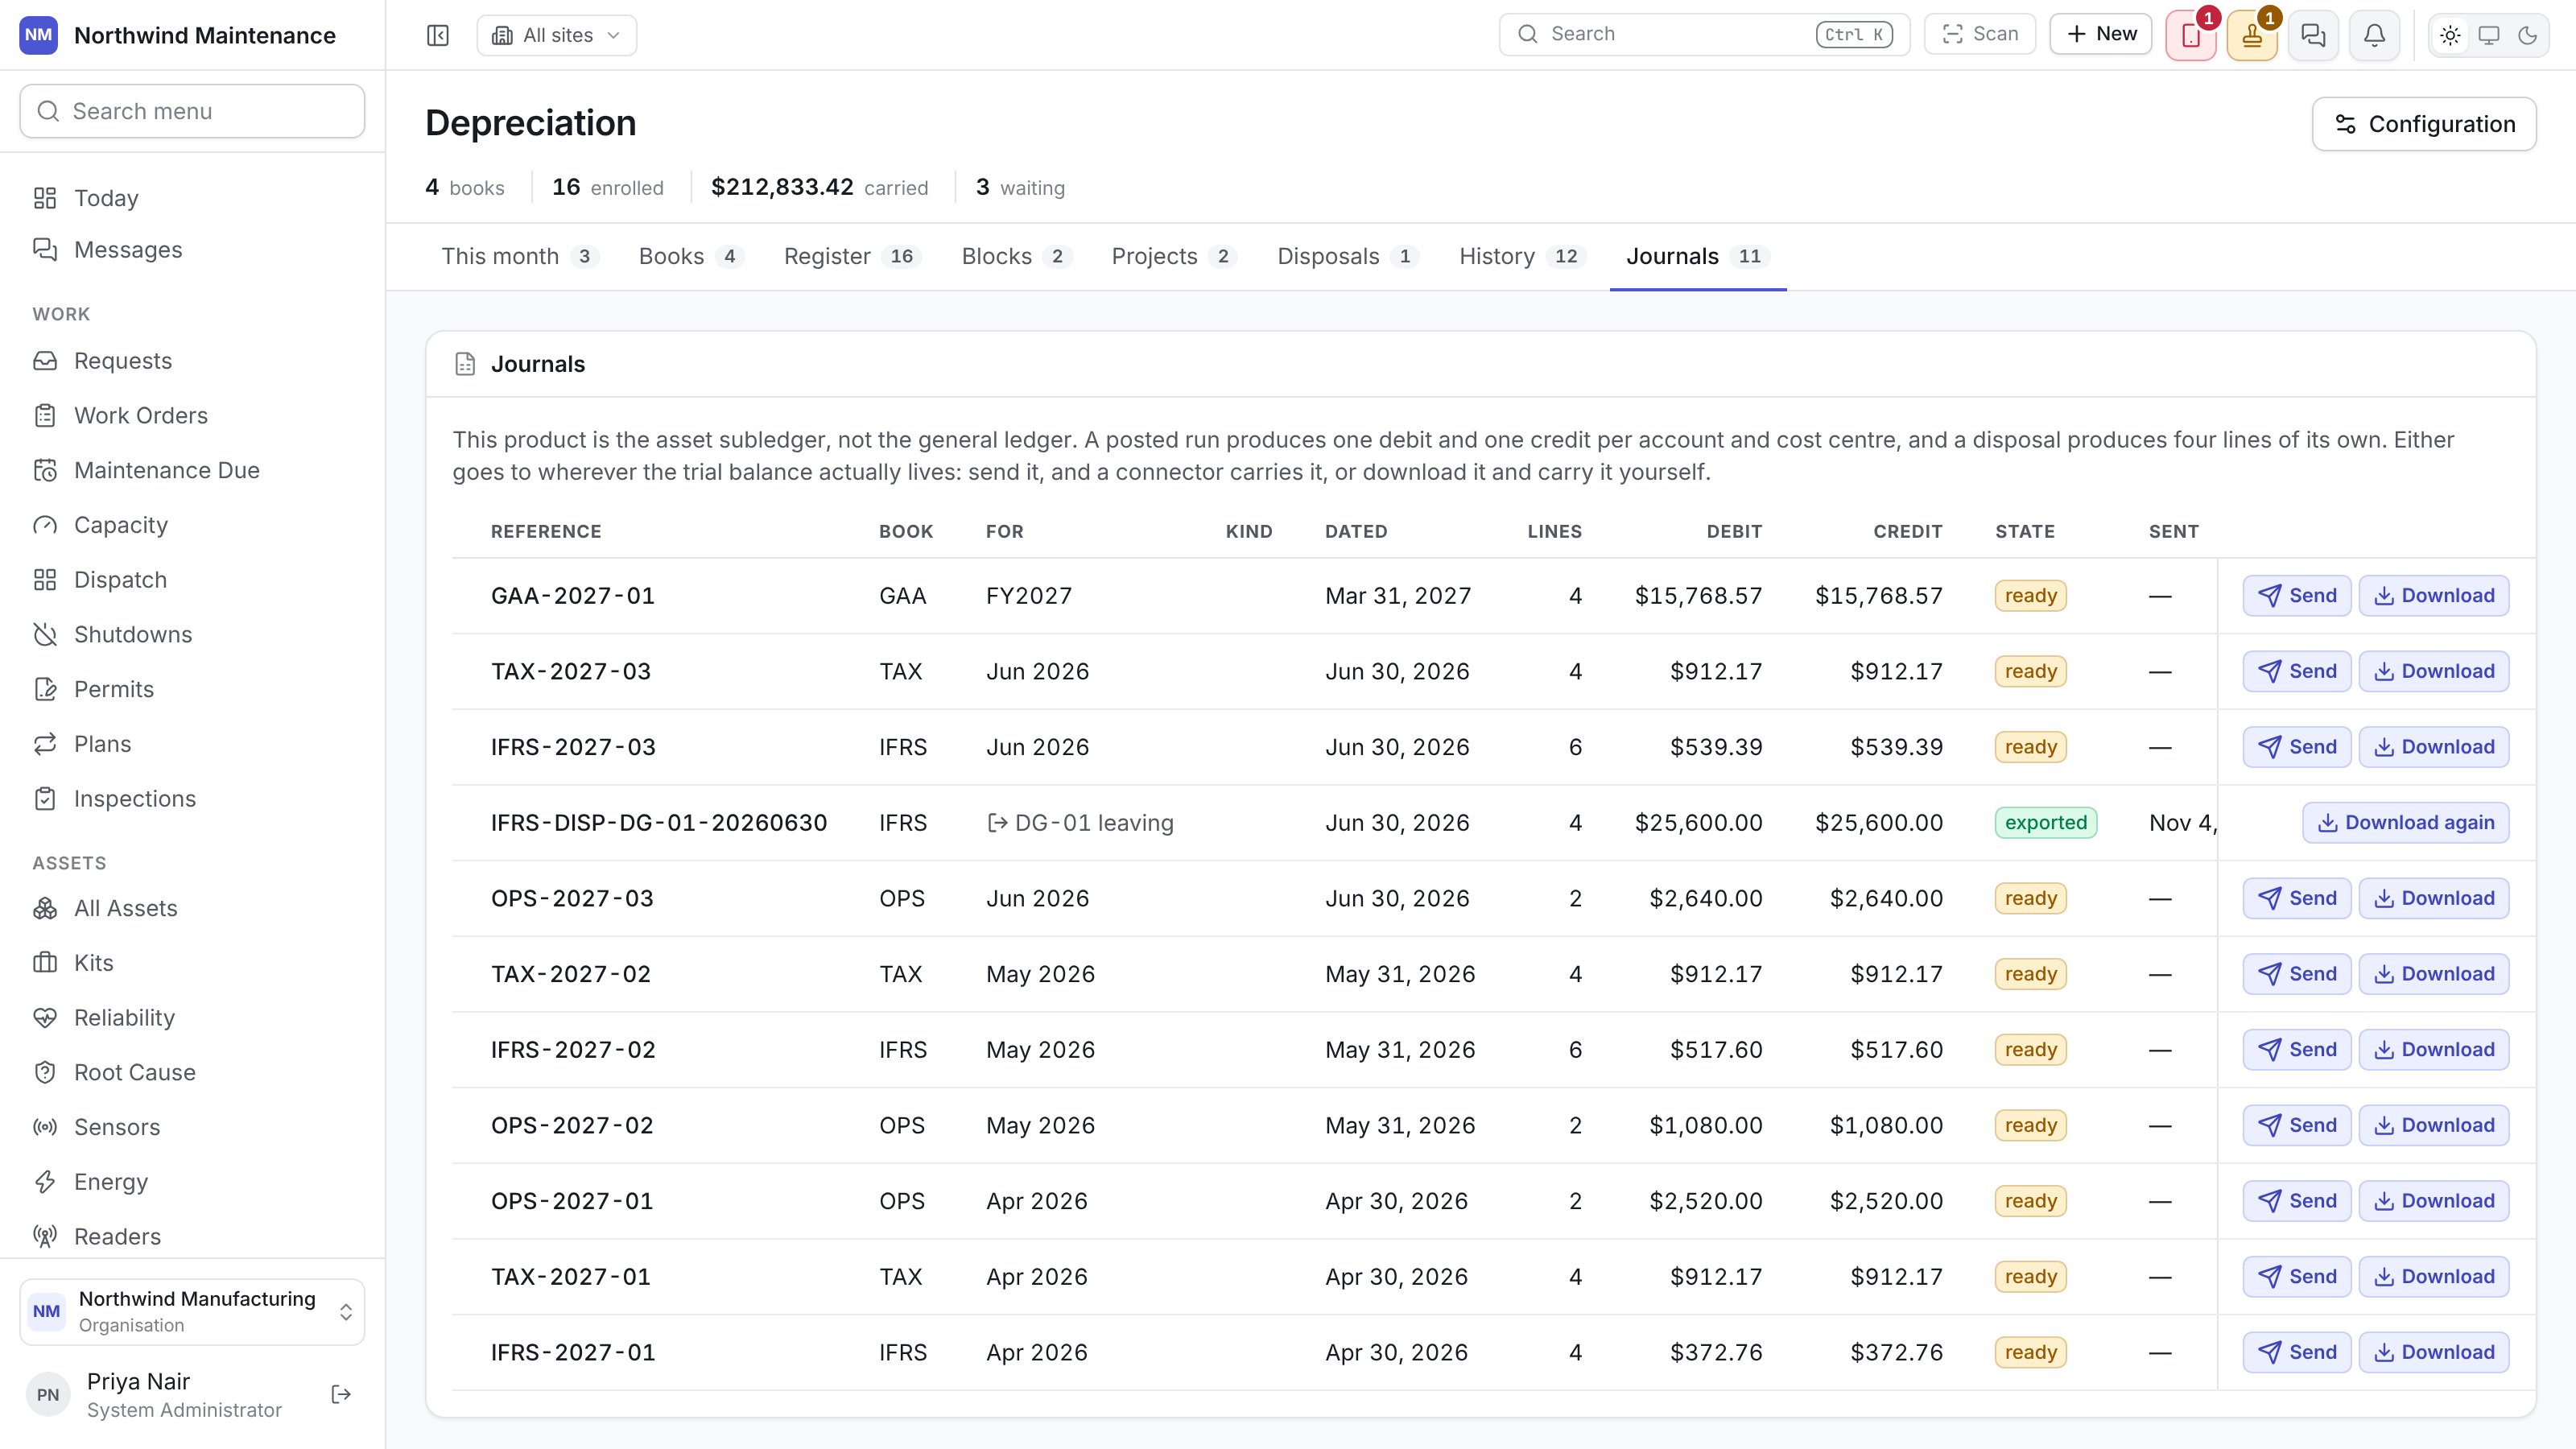
Journals ready to hand to the ledger, with Send and Download Journals ready to hand to the ledger, with Send and Download This product is the asset subledger, not the general ledger. A posted run produces one debit and one credit per account and cost centre; a disposal produces four lines. Journals lists Reference, Book, For (the period, or a disposal), Kind, Dated, Lines, Debit, Credit, State (ready, exported) and Sent. Send hands a batch to the ledger through a configured connector; Download saves it for you to load yourself (Download again once sent). Both need Hand a journal batch over to the ledger.

On an asset

An asset’s own Finance tab (shown where depreciation is switched on) has its carrying amount in every book side by side, the dated cost events its basis is built from, and Capitalise, revalue, revise and Dispose directly against the asset. See inside an asset.

Configuring depreciation

Country packs, books, classes, policies, rules and ledger accounts.

India: GST and depreciation

Companies Act and Income-tax Act books side by side.